
Getting a mortgage in Newport Beach
On the Peninsula and Balboa Island the standard building is two homes on one lot, and that changes the loan more than the price does. A file here is often underwritten twice — on you, and on what the other unit earns — under rules that exist for exactly that shape of property. Add the county's highest prices and a great deal of income that does not look like a pay stub, and the rest of the picture fills in. Here is how it works, in the order it comes up.
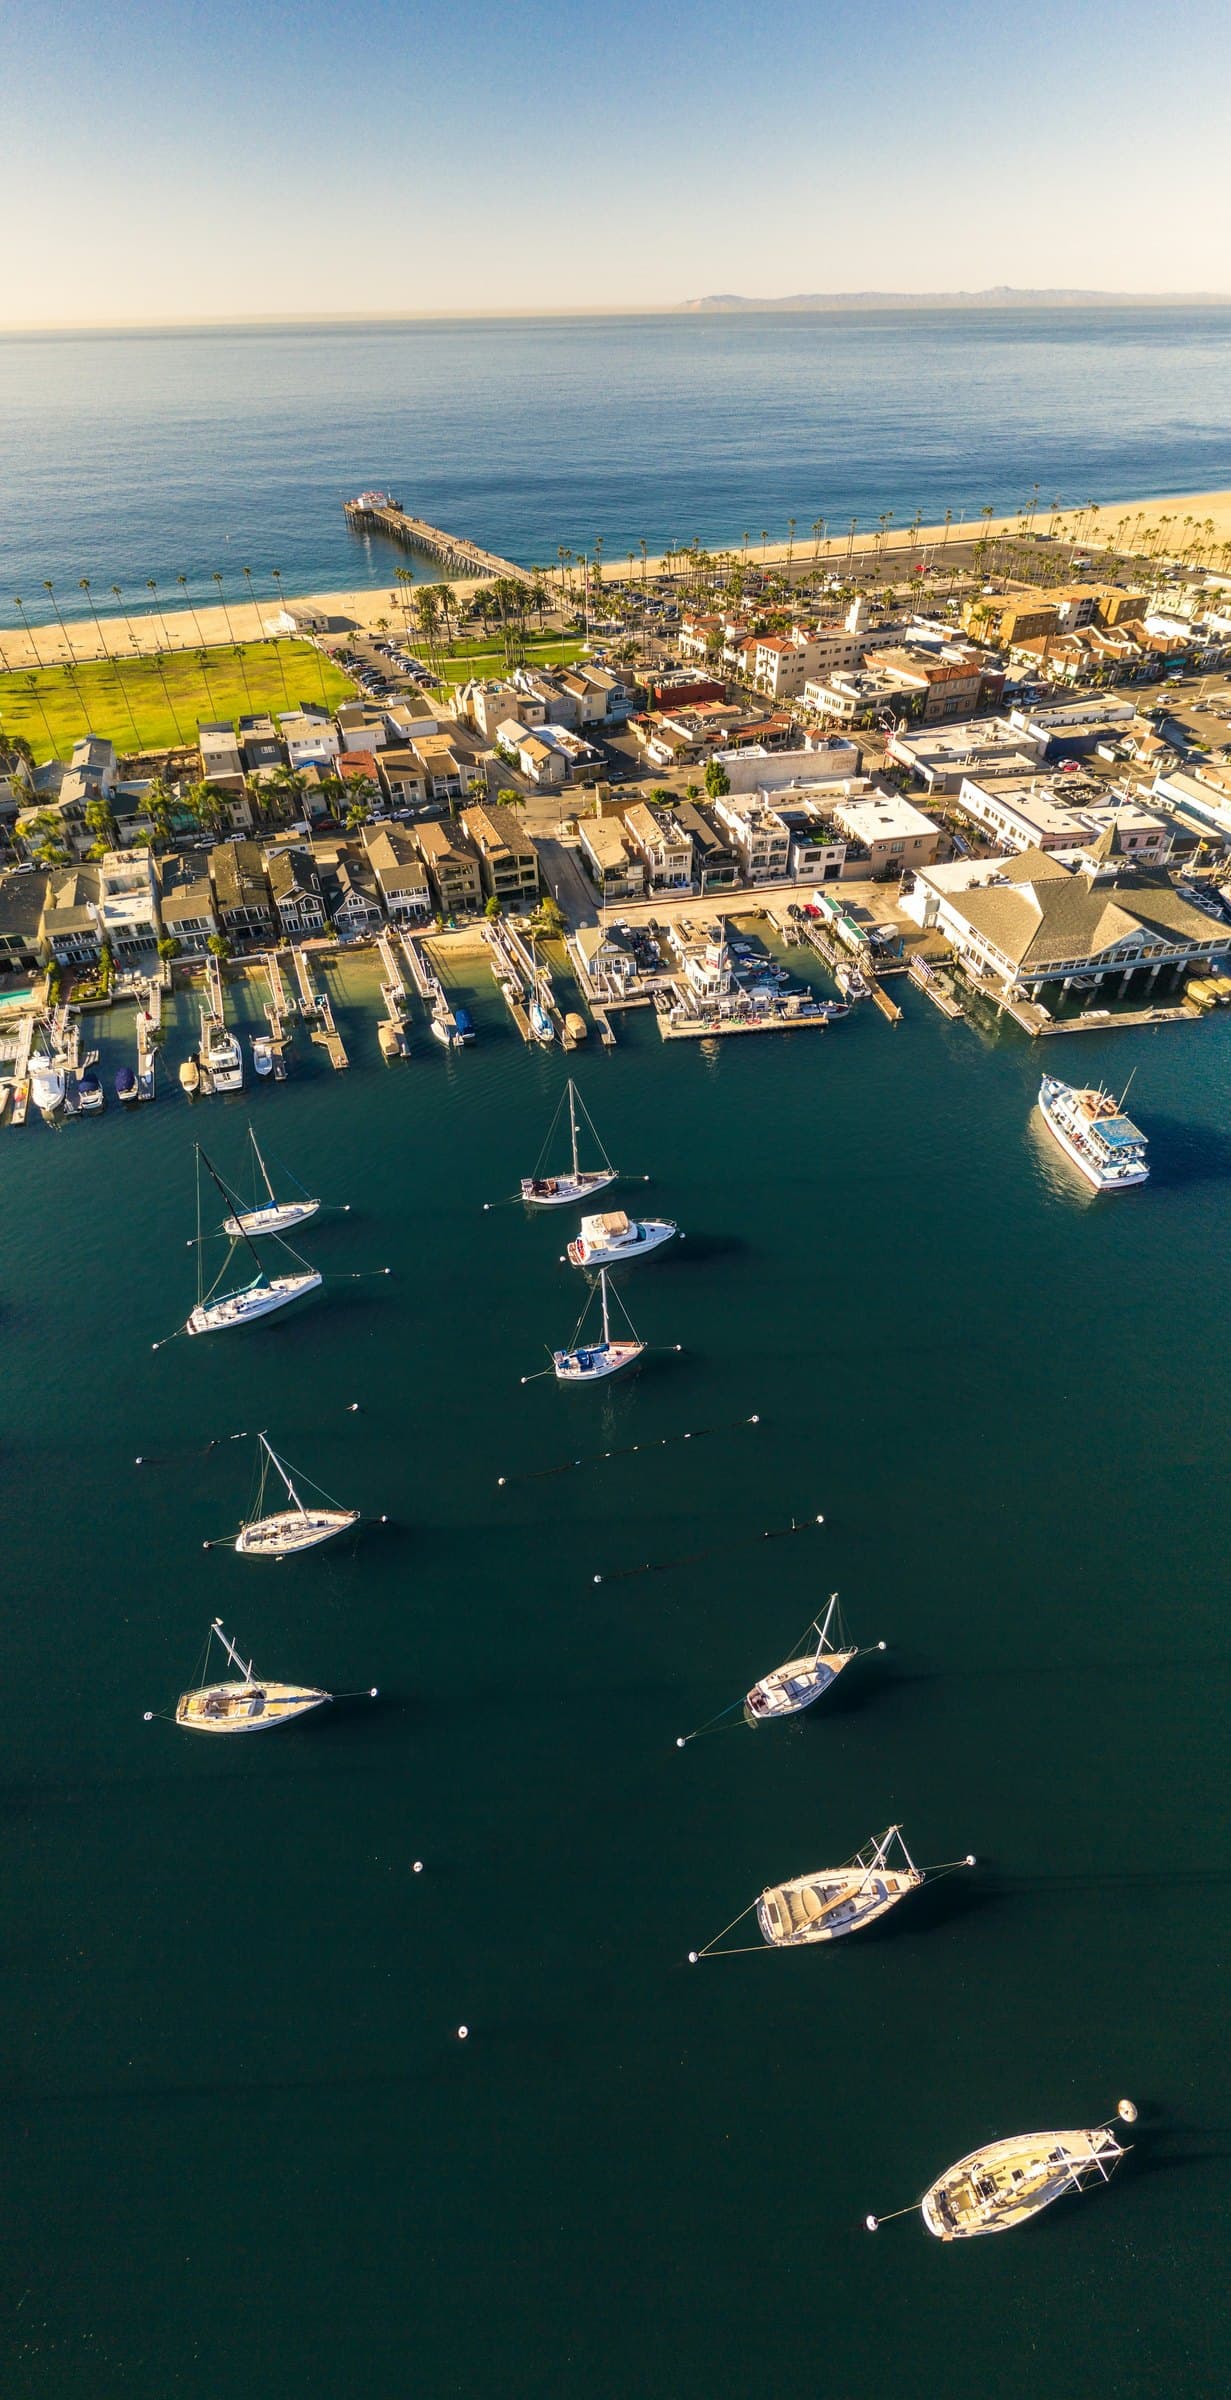
Newport Harbor from above — the pier, the moorings, and the Peninsula's lots between them.
One lot, two homes
What makes a Newport Beach mortgage different?
Because the standard building on the Peninsula and Balboa Island is two homes on one lot. When one of them will be rented, a lender underwrites the property's income as well as yours, on an appraisal that includes a rent schedule, under rules written for exactly this. Most of what is different here follows from that.
The unit you live in
Underwritten on youThe unit that pays rent
Underwritten on the propertyThe city's own zoning code says it plainly: the districts that cover most of the Peninsula and all of Balboa Island are intended for a maximum of two dwelling units on a single legal lot. That is why so much of what sells there is a duplex, a house with a unit over the garage, or a front-and-back pair — and why a buyer who set out looking for a house ends up, more often than anywhere else in the county, financing a small income property.
A lender treats that as a different kind of file, and the difference shows up before underwriting does. The appraisal is a different report, one that carries a schedule of what the units rent for. The occupancy question — which unit you will live in, or whether you will live there at all — decides which rulebook applies. And the rent, once it is documented, becomes a number on your side of the ledger rather than the seller's.
None of that is harder than a single-family purchase. It is more specific, and the specificity rewards knowing the shape of the file before you write, because the same address financed as a home you live in and as a pure investment are two different loans with two different sets of paperwork.
Who is buying
Who is actually buying in Newport Beach?
Three groups, and they need three different files: business owners whose income does not look like a pay stub, investors weighing a duplex or a small building as a rental, and families moving up who are financing a larger loan than they have before. The property question above cuts across all three.
The business owner is the common case here, and the surprise for them is rarely the price. It is that a tax return written to minimize what a business shows the government is also the document a conventional lender reads to decide what the business earns. The complicated-income section further down is about that, and it is a short section because the answer is a program rather than a problem.
The investor arrives with a different question, and usually a duplex or a triplex in mind. What they want to know is whether the property can carry itself, and the honest answer is that a lender asks the same thing — with its own arithmetic, its own allowance for vacancy, and its own view of what counts as documented rent. The two sections after this one are that arithmetic, in both directions.
The move-up buyer — Newport Heights comes up, the newer townhomes come up — is financing a bigger number than before and often crossing the county's conforming line for the first time. The jumbo page carries what changes across that line; the section on the limit below carries the one thing about it that is specific to a city full of multi-unit lots.
Rent that counts
If I live in one unit and rent the other, does the rent help me?
Usually, yes — with conditions. When you live in one unit, rent from the other can count toward the income a lender uses, documented by a lease or by the rent schedule in the appraisal, and reduced by an allowance for vacancy before any of it counts. If you have never been a landlord, how far it carries you is capped.
- Rent a lender can count
- Allowance for vacancy, set by the guide
The guide is explicit that a two-to-four unit property in which the borrower occupies one of the units is a principal residence, and that rent from the other units is eligible for qualifying. That single sentence is what makes a Peninsula duplex reachable for a buyer who could not carry the whole payment alone: the property helps pay for itself, and the lender is allowed to count that.
Three conditions do the work. The rent has to be documented — a current lease if the unit is occupied, or the rent schedule the appraiser completes as part of the report. The lender sets a share of it aside for vacancy before counting the rest, so the number that reaches your file is smaller than the number on the lease. And if you have no history of managing a rental, the guide caps what the rent can do: it can cover the property's own payment, but it cannot lift you beyond that into a larger loan.
That cap is the part first-time buyers of a duplex most often have not heard, and it is worth hearing early. It does not stop the purchase. It means the rent makes the property affordable rather than making you a bigger borrower, and the difference decides which duplexes are within reach.
The practical version: bring the listing's rent figures and any existing leases to the first conversation, and expect the appraiser's schedule to be the number that finally counts. A lease that says one thing and a rent schedule that says another is a common way for a file to lose a week.
The investor's path
What if I'm not going to live there?
Then it is an investment property, and the file changes shape rather than getting harder. The occupancy is different, the reserves a lender wants are different, and the documentation can go one of two ways: the conventional route, which reads your income and the rent together, or an investor route that reads the property's rent on its own.
- A principal residence
- The other unit's rent counts, less the allowance
- Capped at the property's own payment if you have never been a landlord
- The more generous rulebook
- An investment property
- More of your own money in the deal
- Reserves to carry a vacancy
- Conventional route, or an investor route that reads the building alone
The guide's definition is short — an investment property is one the borrower owns but does not occupy — and everything downstream follows from it. A lender expects more of your own money in the deal, expects to see reserves after closing that would carry the property through a vacancy, and reads the rent with the same allowance set aside as above, but without the owner-occupant's advantages.
The two documentation routes are the real decision. The conventional route underwrites you: your income, your other obligations, and the property's rent alongside them. The investor route underwrites the building: whether what it rents for covers what it costs to carry, with your personal income much less in the picture. The investment-property page on this site lays both out; which one fits depends on the deal, and on how your tax returns read.
One thing that is not a route: buying as an owner-occupant with no intention of occupying. Lenders read occupancy carefully on a two-unit lot precisely because the owner-occupied rules are more generous, and a file that says one thing and does another is a problem that outlasts the closing. Decide which of the two you are, and finance that.
Above the limit
Isn't everything in Newport Beach a jumbo loan?
Less often than the prices suggest, because the conforming limit rises with the number of units. A duplex is tested against a higher ceiling than a house, a fourplex against a higher one still. Above whichever line applies, you are in jumbo, where lenders differ on everything and the appraisal gets read very closely.
Above whichever line applies, the loan is jumbo. The county's figures by unit count are on the Orange County jumbo page, pinned to the agency that publishes them.
This is the one fact about the conforming limit that a city of two-unit lots changes. The limit is a county figure, but it is set per unit count — one figure for a single home, higher figures for two, three and four units — and the figures themselves live on the Orange County jumbo page, pinned to the agency that publishes them and re-checked each January rather than retyped here. What matters on this page is the shape: the same loan amount can be jumbo on a house and conforming on the duplex next door.
Above the line, the county's highest prices meet the strictest underwriting, and the place it shows first is the appraisal. Larger loan amounts often mean a second opinion of value or a desk review, and on a multi-unit property the reviewer is reading the rent schedule as carefully as the comparable sales. A value that lands short does not vanish the difference; it moves it onto you, and that is a conversation to have before an offer rather than during a contingency.
Lender choice matters more up here than anywhere else in the county, because each one writes its own rules on reserves, on what documentation of rent it will accept, and on whether it wants a multi-unit jumbo at all. Some do not. The shortlist is the first thing to settle, and it is far easier to change before an offer than after.
Complicated income
My income is complicated. Does that end the conversation?
No. It changes which documents carry the file, not whether there is one. Tax returns that understate what a business really earns are the ordinary case here, and there are programs built for it — bank statements in place of returns, or assets in place of income. The cost is a narrower shortlist of lenders and a closer read.
The specialty and non-QM page on this site describes each of those programs; this section is only about how they meet the property question above. A bank-statement loan on a duplex you will live in still reads the other unit's rent, with the same allowance for vacancy, so the two halves of the file combine rather than compete. On an investment purchase, the investor route that reads the property's rent on its own is often the cleaner answer for exactly the borrower whose returns understate them.
What every version has in common is that the shortlist gets shorter. Fewer lenders write these programs, fewer still write them on multi-unit property, and fewer again above the conforming line. That is not a reason for pessimism — the lenders who do this do a great deal of it — but it is a reason to have the conversation about documentation on the first call rather than after an offer is accepted.
If a friend were buying in Newport Beach, I'd tell them to really think about the lifestyle they want, because Newport Beach can feel completely different depending on where you buy. Newport Heights, the Peninsula, Eastbluff, Dover Shores, and Corona del Mar all offer something different. Don't just focus on being 'in Newport' — find the neighborhood that actually fits how you want to live.
Newport Beach questions I get asked
- Can the rent from the other unit help me buy a duplex?
- When you live in one unit, usually yes. The guide treats the property as your residence and lets documented rent from the other unit count toward the income a lender uses, after an allowance for vacancy. If you have never managed a rental, that rent can cover the property's own payment but not carry you beyond it.
- Do I need to have been a landlord before?
- No, but it changes what the rent can do. Without a history of managing rental property, the guide caps rental income at the property's own payment — enough to make the duplex affordable, not enough to make you a larger borrower. With a history, documented on your returns, the cap comes off.
- Is a Newport Beach duplex automatically a jumbo loan?
- Not automatically. The conforming limit rises with the number of units, so a duplex is tested against a higher ceiling than a single home at the same loan amount. The county's figures by unit count are on the Orange County jumbo page. Above whichever applies, you are in jumbo, and lender choice becomes the first decision.
- Can I finance a Newport rental without showing my income?
- Some investor programs read the property rather than you — whether what it rents for covers what it costs to carry — and put your personal income much less in the picture. They come with their own terms and a shorter list of lenders. The investment-property page describes them; whether one fits depends on the deal.
- What is different about the appraisal on a two-unit property?
- It is a different report, and it carries a schedule of what the units rent for alongside the comparable sales. That schedule is usually the rent figure that finally counts on your file, whatever the listing said. On larger loan amounts it is also the document a second reviewer reads most closely.
- Do you actually work in Newport Beach?
- Yes — it is one of the areas I work, and the reason this page is about two-unit lots rather than about the beach is that the second unit is what actually changes a loan here. Bring me the address and which unit you would live in, and the rest of the conversation is mostly arithmetic.
Where to go from here, if one of these is closer to your actual question:
- Orange County jumbo loansthe conforming limits themselves, by unit count, with where they come from and when they were last checked — and everything that changes once a loan crosses one.
- DSCR and investment property loanswhat happens to the same rent when you do not live there — how it lands in your own debt ratio instead, and the three points where that route runs out.
- Investment property loansthe investor route in full — programs that read the building's rent rather than your returns, and the conventional route beside them.
- Specialty and non-QM loansbank-statement and asset-based documentation, for the business owner whose returns understate the business.
- Costa Mesa mortgage brokerthe city next door, where the question is the loan limit on a single house rather than the second unit on the lot.
Where the guideline and city material came from
The rules about rent are Fannie Mae's, read from the guide itself and dated; the fact about the lots is the City's, read from its own zoning code. Nothing here is from a listing or a blog. Go and check it against the source rather than against me.
- Fannie Mae's Selling Guide treats a two-to-four unit property in which the borrower occupies one of the units as a principal residence and allows documented rental income from the other units to be used in qualifying, after an allowance for vacancy; where the borrower has no history of managing rental property, the rental income used may not exceed the property's own housing payment.Read at the source on
- Fannie Mae's Selling Guide defines a principal residence as a property the borrower occupies as their primary residence, and an investment property as one the borrower owns but does not occupy.Read at the source on
- The City of Newport Beach Zoning Code states that its two-unit residential districts — including the district covering Balboa Island — are intended to provide for a maximum of two residential dwelling units on a single legal lot, and that its single-unit district does not include condominiums or cooperative housing.Read at the source on
Tell me which unit you'd live in, and I'll tell you the rest.
On a Newport lot the useful questions are about the property before they are about you: one home or two, which one is yours, what the other one rents for, and how your income is documented. That is enough to say which rulebook reads the file and which lenders are worth a call.
- Call or text
- (949) 744-5302
- Office
- 17911 Von Karman Ave, Suite 400
Irvine, CA 92614