
Getting a mortgage in Huntington Beach
This is the county's biggest beach city, and most of it finances like the county around it. But a meaningful share of what is listed here is a home on land the seller does not own — a manufactured home in a community where the ground is rented by the month — and that is a different kind of purchase with a different kind of loan, or no mortgage at all. Knowing which one a listing is before you write an offer is most of what this page is for.
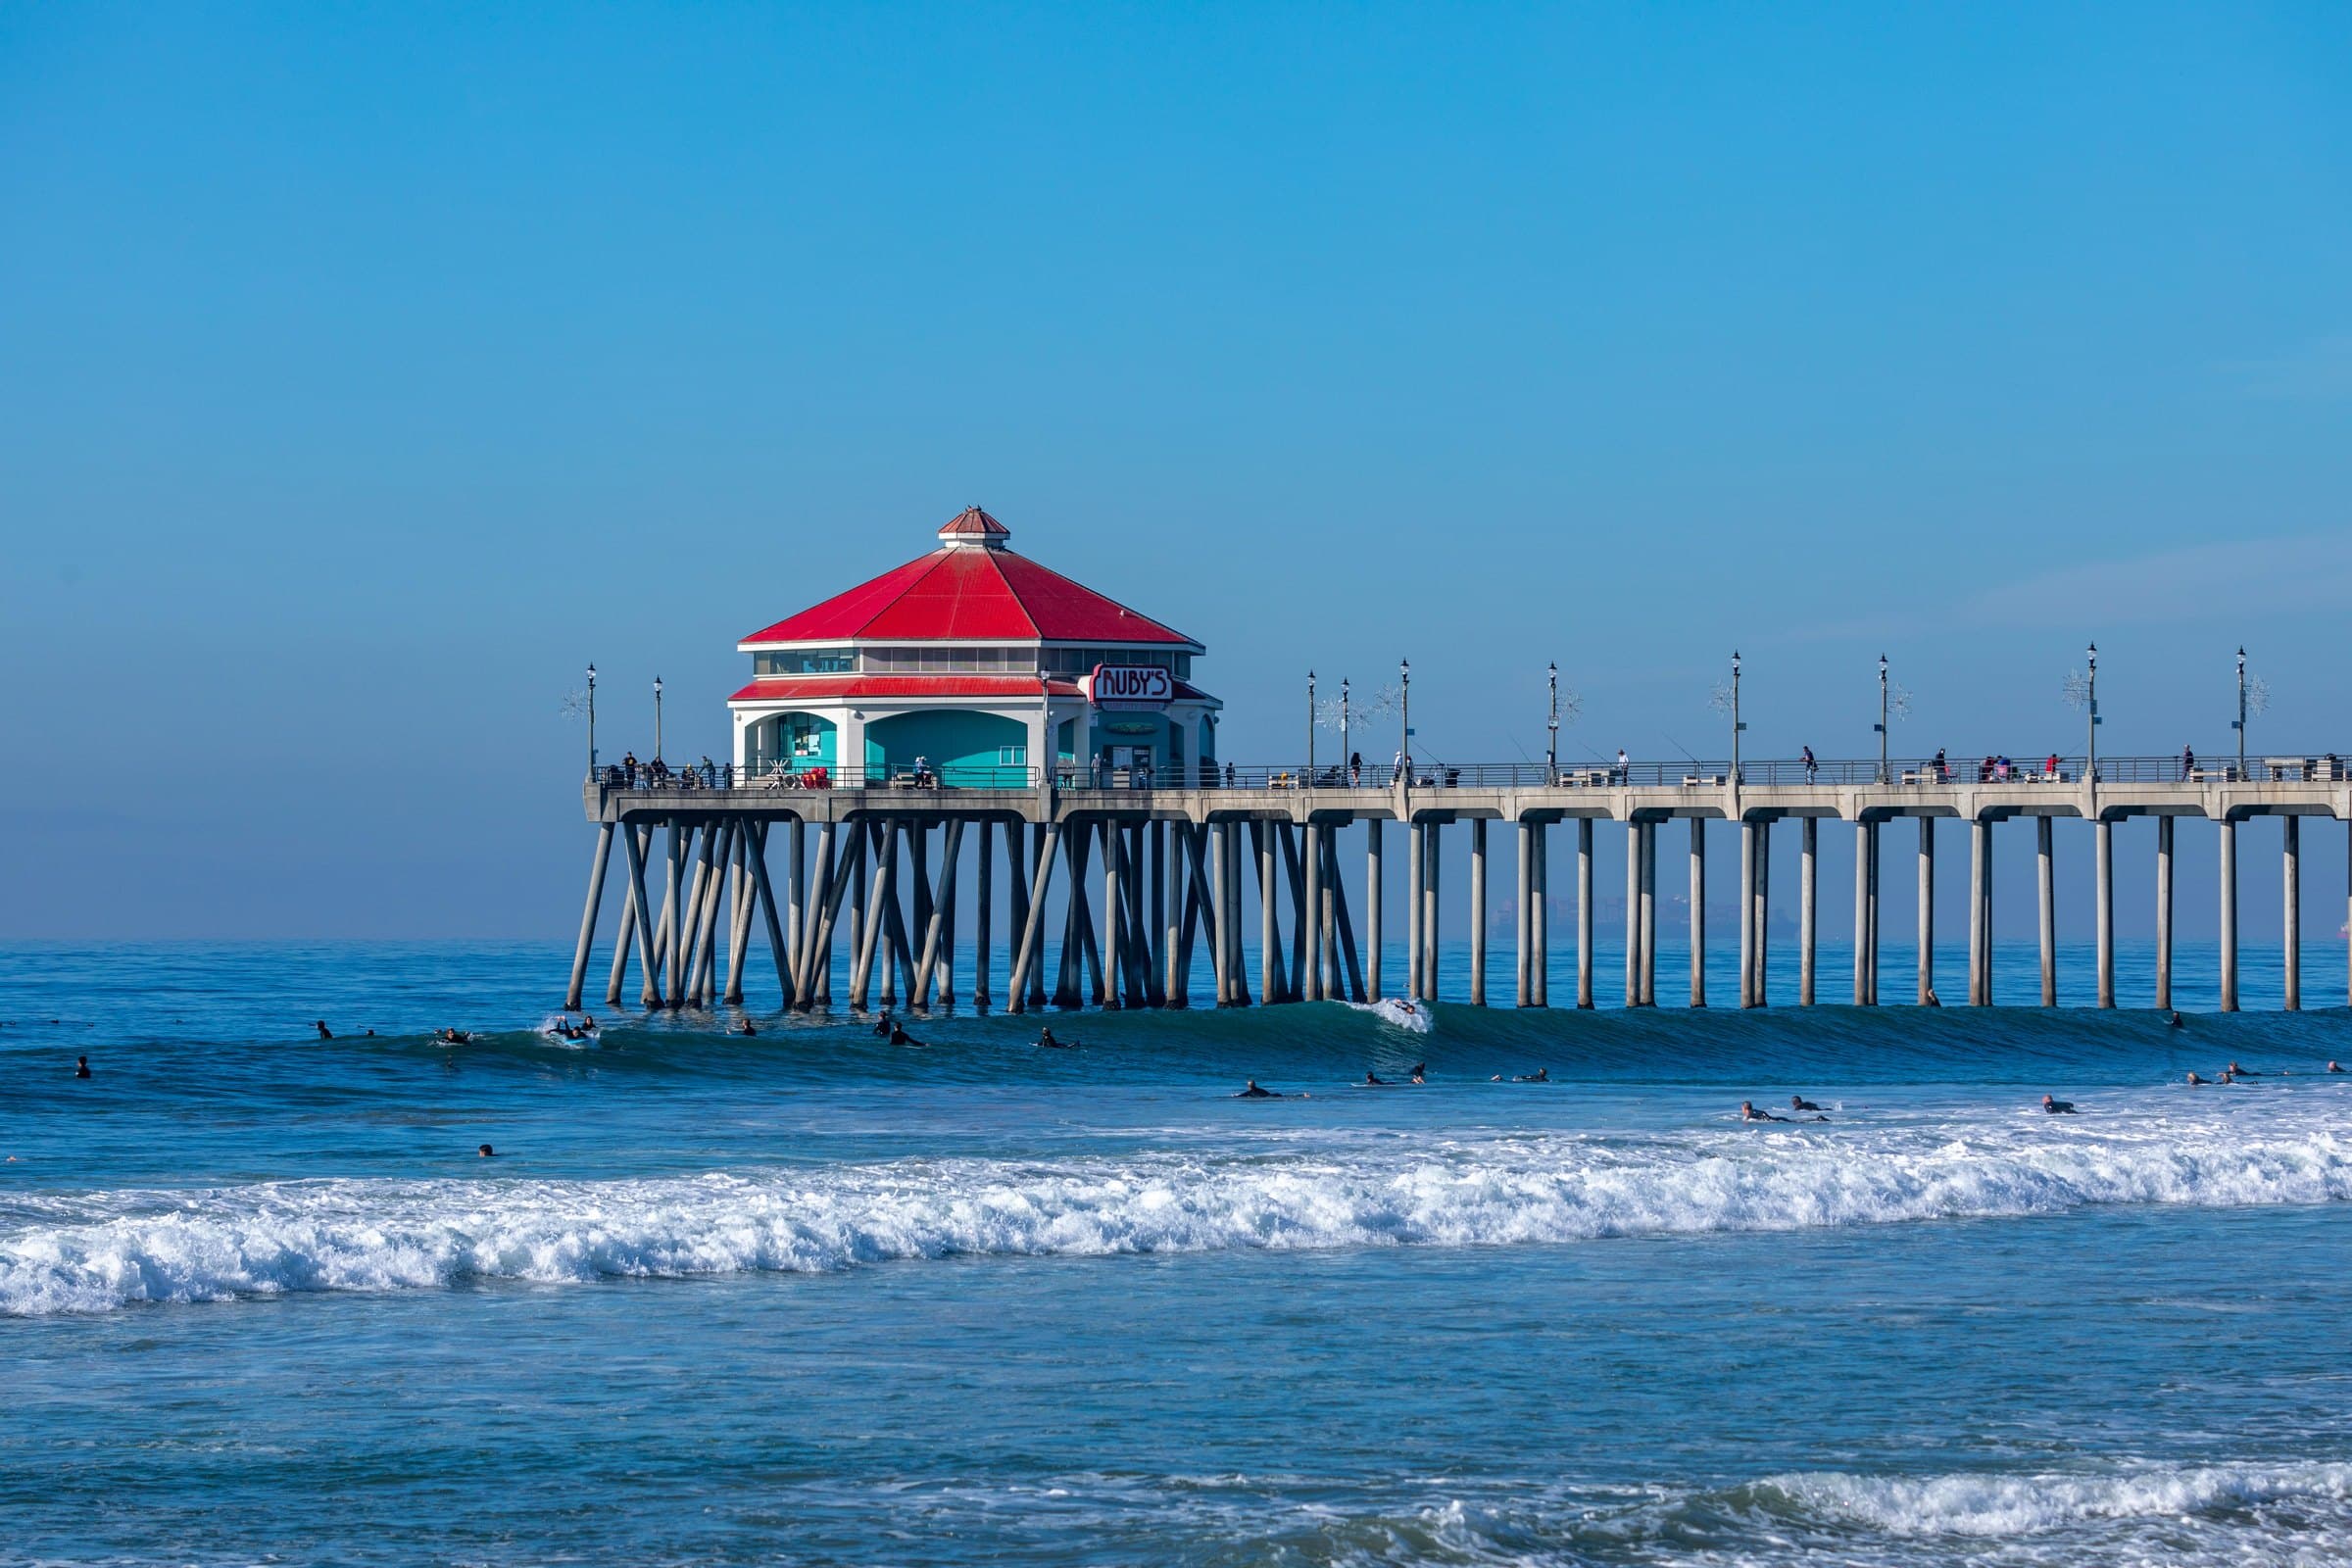
The Huntington Beach pier from the water — the coast the insurance is priced for.
Space or lot
What makes a Huntington Beach mortgage different?
Because a fair amount of what is for sale here is a home on land somebody else owns. Huntington Beach has enough manufactured-home communities that the city keeps a standing board for them, and a home in one is financed in a completely different way from a home on its own lot — sometimes not with a mortgage at all.
- No
Do you own the ground the home sits on — deeded, taxed with the home?
YesA mortgage. Conventional programs exist for manufactured homes on owned land.
- No
Is the community itself an approved project with the agency?
YesPossibly a mortgage — rare, and the file starts with that question.
A personal-property loan from a lender who writes them — not a mortgage, and not something this site offers.
There are two kinds of ownership at work, and they look alike in a listing. In the first, you buy the home and the ground under it together, and the home is attached to the land and taxed with it — real property, in the plain sense. In the second, you buy the home and rent the space it sits on from the community that owns the land. The home is yours; the ground is theirs; and to a lender that difference is the whole file.
The guide most lenders write to is explicit that the home and the land have to be classified as real property together for a conventional mortgage. A home on rented land in a community qualifies only where the community itself has been approved as a project by the agency, and that is rare. So a home on a rented space is, almost always, financed as personal property — a different product, from a different kind of lender, with different terms.
The city takes these communities seriously enough to have kept an advisory board for them since the nineties — park owners, resident owners and citizens at large, advising the council. That is a good sign for anyone who lives in one. It does not change what a mortgage lender can do, and I would rather say that on this page than on the first call after you have fallen for a listing.
Which one is it
How do I tell whether a listing is a mortgage or something else?
Ask who owns the ground. If the home sits on a lot you would own, attached to it and taxed with it, it can be financed like a house. If the listing comes with a monthly space rent to a park, the land is the park's, the home is personal property, and the loan is a different product altogether.
| The listing | What you own | How it is financed |
|---|---|---|
| Home and lot | The house and the ground, together, as real property. | A mortgage, on programs written for manufactured homes on owned land. |
| Home on a rented space | The home only. The land belongs to the community. | A personal-property loan from a different kind of lender. Not a mortgage. |
The listing usually tells you, if you know where to look: a space rent, a community name, a lease on the land. The title record settles it. A home that has been converted to real property shows on the county roll with the land it sits on; a home that has not is registered separately from the ground, and the ground has a different owner.
On the first kind, I can help, and the loan is ordinary in most respects. There are conventional programs written specifically for manufactured homes on land the borrower owns, with their own standards for how the home was built and set, and the file otherwise reads like any other purchase. On the second kind, I will tell you plainly that a mortgage is not the tool, and point you toward the lenders who write personal-property loans on homes in communities — rather than string you along for a month.
One more thing worth knowing if you already live in one of these communities: the city runs a rental-assistance program for mobile-home tenants, and its own page on mobile-home information links the park map, the dispute procedures, and that program. The city's page is among the sources at the bottom, dated to the day it was read.
The rest of the city
And the houses, condos and townhomes?
Those finance the way they do anywhere else in the county, and the two questions that come up most are ones this site already answers at length: an older tract house that has been added onto, and an attached condo where the association has to pass its own review. Both pages are linked from here.
The tract neighborhoods inland of the highway were largely built in the sixties and seventies, and a great many of those houses have been added onto since. What that does to an appraisal — which square footage counts, why the permit history is worth pulling while you are still shopping — is the older-houses section of the Costa Mesa page, and it applies here without a word changed.
The condos and townhomes raise the other question: a lender underwrites the association as well as the buyer, and the rules for that review tightened this year. The Irvine page is about exactly that, and the figure on it that walks through which projects get waived and which get the full review is the one to read before you write on an attached unit here.
And the conforming line runs through this city the way it runs through Costa Mesa: two buyers agreeing the same price can land on opposite sides of it, because the limit is tested against the loan and not the house. That page covers it; the down payment is the number to settle first.
Near the water
Does being near the beach change the loan?
Not the loan itself, but two lines in the payment a lender tests you against. Insurance is one — coverage a lender requires, priced for where the house is. And some addresses carry a flood-insurance requirement on top, which is the lender's condition to fund, not a choice. Both belong in the budget before the offer.
- Principal and interest
- Property taxes
- Hazard insurance, priced for the coast
- Flood insurance
Hazard insurance is a condition of every mortgage, and on a coastal address it is priced for the coast. That is not a Huntington Beach quirk; it is a line in the monthly figure a lender measures your income against, and the quote is worth getting before the offer rather than after, because it moves the number you are shopping to.
Flood coverage is the second line, and it is not optional where it applies. A lender checks the address against the flood maps as part of the file, and where the property falls in a designated zone, flood insurance becomes a condition of funding — required at closing and carried for the life of the loan. Which addresses that covers is a map question, not a guess, and the answer is knowable before you write. Ask for it.
Neither of these is a reason not to buy near the water. Both are reasons to put the whole payment — principal and interest, taxes, insurance, and any flood policy — in front of you before the offer rather than discovering the last two lines in escrow.
If a friend were buying in Huntington Beach, I'd tell them to pay attention to how close they actually want to be to the beach. Being west of PCH or close to Downtown is a completely different lifestyle and price point than some of the neighborhoods farther inland. Huntington is a big city, so I'd focus on finding the pocket that gives you the best combination of lifestyle, commute, and value.
Huntington Beach questions I get asked
- Can I get a mortgage on a mobile home in Huntington Beach?
- If you would own the land under it, usually yes — there are conventional programs for manufactured homes on owned lots. If the home sits on a rented space in a community, almost never: the land is not yours, and the loan is a personal-property product from a different kind of lender.
- How do I know whether the land is included?
- The listing will usually say space rent, lease, or a community name if it is not. The title record settles it: a home converted to real property shows on the county roll with the land it sits on. Ask before you get attached, and I will confirm it on the first call.
- Will you help me with a park home even if you cannot write the loan?
- I will tell you the truth about it, which is what most people actually need: whether the address is a mortgage or not, and where to go if it is not. That takes one call. What I will not do is let you spend a month in escrow finding out.
- Do I have to buy flood insurance near the beach?
- Where the address falls in a designated flood zone, a lender requires flood coverage as a condition of funding, and it stays for the life of the loan. Whether a given address is in one is a map question with a definite answer, and it is worth asking before the offer rather than in escrow.
- Is a Huntington Beach house a conforming loan or a jumbo loan?
- Either, and the price alone will not tell you. The conforming limit is tested against the loan amount, so the same house can land on either side depending on the down payment. The Costa Mesa page walks through that in full; the mechanics are identical here.
- Do you actually work in Huntington Beach?
- Yes — it is one of the areas I work, and this page exists because the honest first question here is different from anywhere else in the county: is this a lot, or a space? Bring me the address and I can usually answer it the same day, along with what the rest of the file will look like.
Pages this one leans on, for the parts of the city that finance like everywhere else:
- Costa Mesa mortgage brokerthe older-houses section is the one to read for the tract neighborhoods here — additions, permits, and what an appraisal counts.
- Irvine mortgage brokerfor the condos and townhomes: how a lender reviews the association, and which projects get waived.
- Orange County first-time buyersdown payment assistance program by program, and an honest read on which ones reach this city's prices.
- Newport Beach mortgage brokerthe next city down the coast, where the question is the second unit on the lot rather than who owns the ground.
Where the guideline and city material came from
The rule about land and home is the investor's, read from its guide; the facts about the city's communities are the City's own. No listing site and no park-count blog is a source here. Check it against them rather than against me.
- Fannie Mae's Selling Guide requires that both a manufactured home and the land be classified as real property for the loan to be eligible, and treats a manufactured home on leased land as eligible only where the borrower owns the home and the community is a condo or PUD project approved through the agency's project review service.Read at the source on
- The City of Huntington Beach maintains a Mobile Home Advisory Board, established as a review board in the nineties, whose purpose is to ensure the quality of life in the city's mobile home parks and to advise the City Council on matters concerning the mobile home community; its members are park owners, resident owners, and citizens at large.Read at the source on
- The City of Huntington Beach's mobile-home information page links a mobile home park location map, dispute-resolution procedures, and a Mobile Home Tenant Based Rental Assistance Program.Read at the source on
Send me the listing before you fall for it.
One question decides most of a Huntington Beach file — is this a lot, or a space — and it is a question with a definite answer. Send the address and I will tell you which it is, whether a mortgage is the tool, and what the whole payment looks like with the insurance a coastal address carries.
- Call or text
- (949) 744-5302
- Office
- 17911 Von Karman Ave, Suite 400
Irvine, CA 92614