
Getting a mortgage in Corona del Mar
The village is old cottages on small lots a few blocks from the water, many of them zoned for two homes, and a great deal of what changes hands here changes hands to be rebuilt. That makes the loan a different exercise: the house in the listing is not the house the lender will end up holding, and the file has to be built around the one that does not exist yet — what it will cost, what it will be worth, and how to get from one to the other.
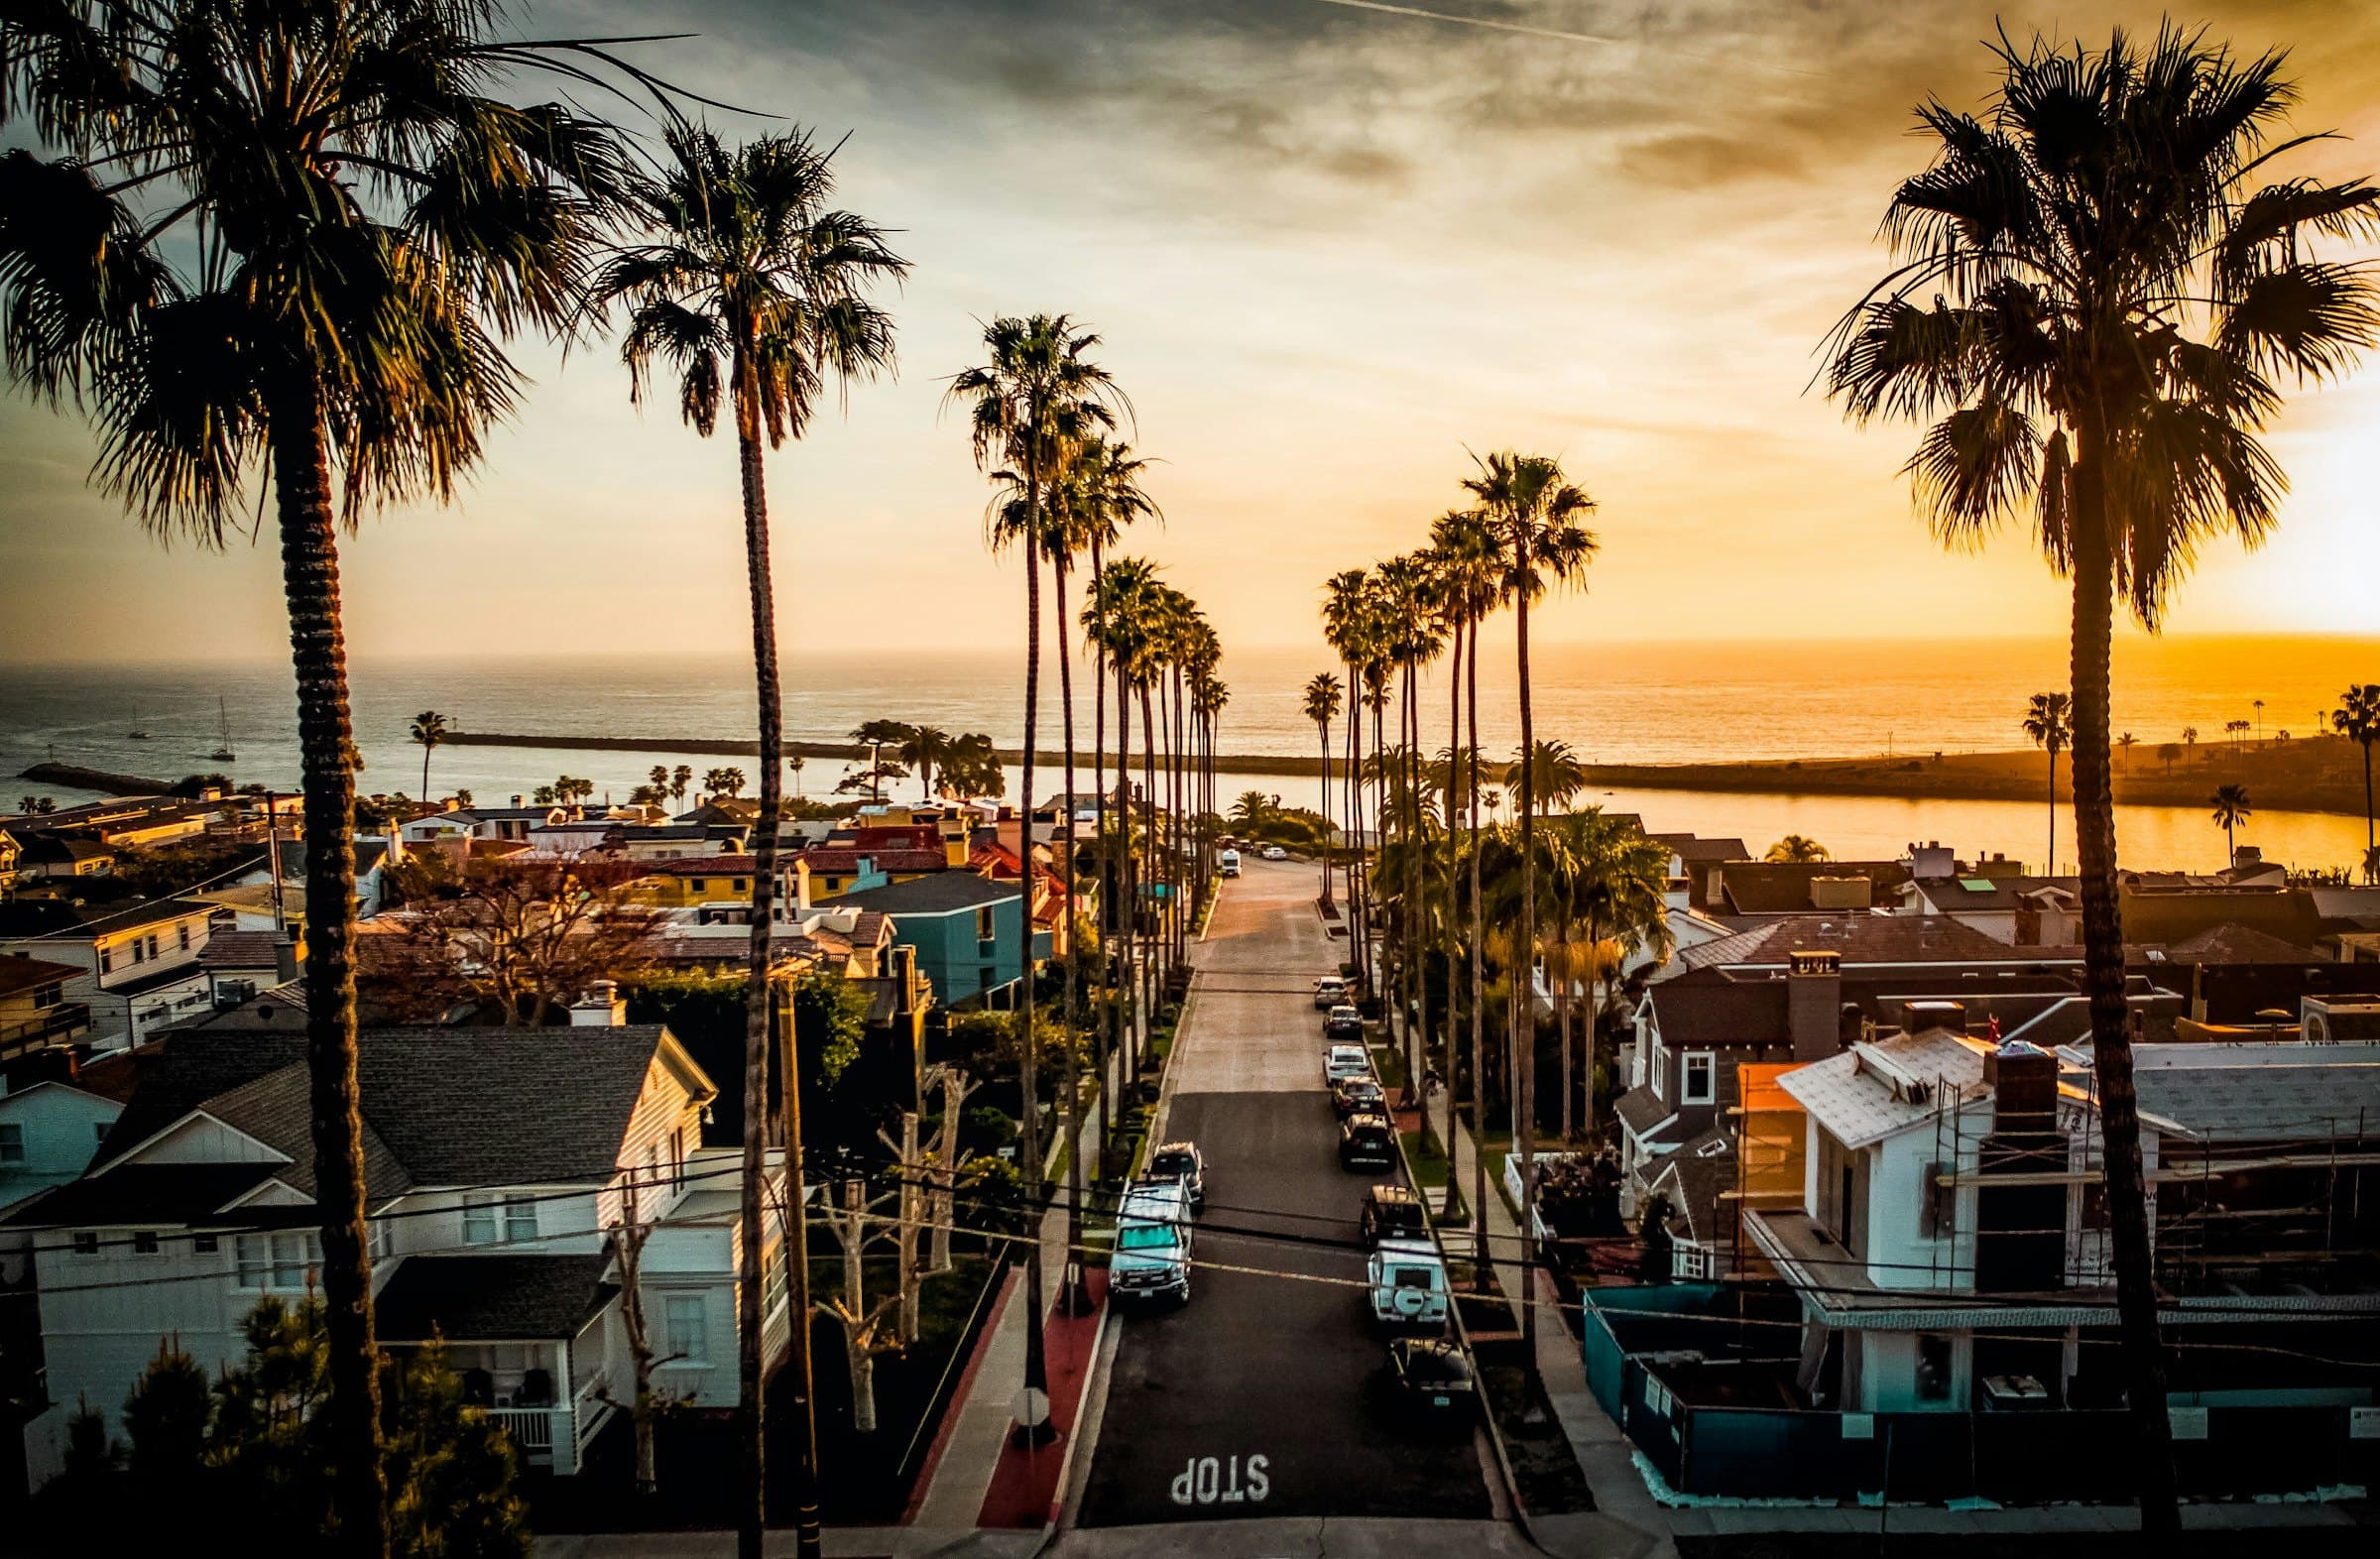
A Corona del Mar street at golden hour, with the harbor beyond.
The lot
What makes a Corona del Mar mortgage different?
Because here what you are paying for may be the ground rather than the house on it. When the plan is to rebuild or gut what is there, the loan has to be structured around the finished house — its cost, its completed value, and the months in between — not around the cottage in the listing photos.
- The lot — the location, the zoning, the street
- The cottage standing on it
The village south of the highway is a grid of small lots, a lot of them holding houses built decades ago, and the city's zoning code puts many of them in a district intended for two homes on one lot. So the stock is cottages, front-and-back pairs, and a growing number of new houses standing where cottages were. A buyer who wants the location and not the house is buying the lot, whatever the listing calls it.
An ordinary purchase loan does not know that. It values the house as it stands, on the day of the appraisal, against what similar houses nearby have sold for. That works when you are keeping the house. It works badly when you are not: the lender is valuing a building you intend to remove, and the money you need for what replaces it is nowhere in the file.
So the first decision on a Corona del Mar purchase is not the lender or the rate. It is what you are going to do with the house — keep it, change it, or replace it — because each of those is a different loan, and the next section takes them in turn.
Three ways
How do you finance a house you're going to tear down?
Three ways, and which one fits depends on how much you are changing. Keep the house and remodel it, and a renovation loan can fold the work into the purchase against the finished value. Replace it, and construction-to-permanent financing carries the lot and the build through to a normal mortgage. Or buy now and finance the build later, separately.
- No
Keeping the house and remodeling it?
YesA renovation loan — the work rides inside the purchase, valued as completed.
- No
Replacing it, and financing the build with the purchase?
YesConstruction-to-permanent — one closing, or two.
Buy first, build later: two separate loans, and the second is underwritten on the finished plans.
The renovation loan is for keeping the house and changing it. The guide's version lets the cost of the work ride inside the purchase loan, with the lender valuing the property as it will be when the work is done rather than as it is on closing day. There is a cap on how much of the total can be renovation, the work is drawn against as it happens, and the house has to remain the house — it is a remodel product, not a demolition one.
Construction-to-permanent is for replacing it. The guide recognizes two shapes: one closing, where a single loan pays for the lot and the build and converts to an ordinary mortgage when the house is finished; or two closings, where a construction loan carries the build and a separate permanent mortgage pays it off at the end. One closing means one set of costs and one qualification; two means more flexibility and a second underwriting when the house is done.
The third way is the simplest and the most expensive in cash: buy the property with an ordinary loan, or without one, and finance the construction later on its own. It separates the two decisions, which some buyers want, and it means qualifying twice against a house that has been valued twice.
Which of the three fits is mostly a question of how much of the finished house you are changing and how much cash you are bringing. The figure beside this is the decision in order; the conversation is the arithmetic under it.
Cost and value
What number is the loan actually based on?
On a purchase-and-build, the lesser of two numbers: what it all costs — the lot plus the construction — and what the finished house appraises for. If building costs more than the result is worth, the difference is yours to bring, and on a street of small lots with big rebuilds that gap is the number to pin down first.
- More cash at closing
- A smaller build
- A different plan for the lot
The guide is specific about this on a single-closing purchase: the loan is measured against the lesser of the purchase price — meaning the price of the lot plus the cost of construction — and the appraised value of the property as completed. The appraisal is written from the plans, against what finished houses of that kind have sold for nearby. It is the same lesser-of rule as any purchase, applied to a house that is still a drawing.
That is where the village bites. A small lot with an expensive build on it can cost more, all in, than the finished house will appraise for, because the appraiser is comparing it with houses that sold before the last few rebuilds reset the street. A lender lends against the lower number. The gap between cost and value does not go away; it becomes cash you bring, a smaller build, or a different plan for the lot.
So get the cost and the likely completed value in front of you before the offer — a builder's real estimate and a broker's honest read of recent finished sales on comparable lots — and run the loan against the lower of them. If the answer is a gap, it is far better found in a spreadsheet than in the second appraisal.
Above the limit
Is a Corona del Mar loan just a bigger jumbo loan?
Mostly, yes, and the size is what changes the room. Well above the conforming limit the number of lenders who want a file shrinks, each one writes its own rules on reserves and documentation, and the appraisal — often two of them — gets read line by line. On a rebuild, the construction lender and the permanent lender may be different people.
The jumbo page covers what changes across the conforming line, and all of it applies here with the volume turned up. What is specific to a rebuild is that jumbo and construction are two shortlists, not one: fewer lenders write large loans, fewer still write construction, and the ones who do both are a short list worth knowing before you make an offer that assumes a loan exists.
The appraisal is the other thing that gets harder with size. A large loan on a finished house often means a second opinion of value; a large loan on a house that is still plans means an appraiser valuing a drawing against a street where the comparable sales may be the last three rebuilds or the last three cottages, and the difference between those two sets is the whole answer. Which set the appraiser uses is worth a conversation before the report is ordered, not after.
One lot, two homes
Some of these lots have two homes on them. Does that change anything?
It changes the same things it changes across the rest of Newport Beach: which rulebook reads the file, whether the second unit's rent can count, and how the appraisal is written. The Newport Beach page covers that in full. What this page adds is what happens when you plan to replace both.
A rebuild on a two-unit lot is usually a rebuild of two units, and the finished property is appraised and underwritten as a two-unit property — a different report, a rent schedule for the unit you will not live in, and the rules about counting that rent that the Newport Beach page walks through. The construction loan has to be sized for both, and the permanent mortgage at the end reads the property as two homes, not one.
If instead the plan is to replace two homes with one large one, that is a different property at the end than at the start, and the appraisal on completion is the thing to think about early: the comparables for a single large house on this street are not the comparables for a duplex, and the lesser-of rule above will use whichever the finished house actually is.
If a friend were buying in Corona del Mar, I'd tell them that you're paying for the location and lifestyle as much as you are the house. Walkability to the Village and the beach, ocean views, parking, lot size, and even which side of PCH you're on can make a huge difference. In CDM, two homes that look similar on paper can offer completely different experiences depending on exactly where they're located.
Corona del Mar questions I get asked
- Can I get one loan that covers buying the lot and building the house?
- Yes. Construction-to-permanent financing can be done as a single closing that pays for the lot and the build and converts to an ordinary mortgage when the house is done, or as two closings with a separate permanent loan at the end. Which fits depends on the build and on your cash.
- What if I want to keep the cottage and remodel it?
- Then a renovation loan is usually the tool — the cost of the work rides inside the purchase, and the lender values the house as it will be when finished. There is a cap on how much of the total can be renovation, and it is a remodel product, not a demolition one. Replacing the house is a different loan.
- What number does the lender use — the price or the finished value?
- The lower one. On a purchase-and-build the guide measures the loan against the lesser of the total cost — lot plus construction — and the as-completed appraised value. If the build costs more than the finished house appraises for, the difference is yours to bring, which is why it is worth knowing before the offer.
- Is every Corona del Mar loan a jumbo loan?
- Nearly all of them, and on a rebuild the loan is large twice: at construction and at the permanent mortgage. Fewer lenders write large loans, fewer write construction, and the ones who do both are a short list. Knowing it before the offer is most of the work.
- Does it matter whether the lot has one home or two?
- It matters at both ends. Today's property is underwritten as whatever it is; the finished one is underwritten as whatever you build. Two units means a rent schedule and the rules for counting the other unit's rent; one large house means different comparable sales. The Newport Beach page covers the two-unit side.
- Do you actually work in Corona del Mar?
- Yes. Corona del Mar is one of the areas I work, and this page is about the lot rather than the beach because the lot is what changes the loan. Tell me what you intend to do with the house and I can tell you which of the three loans it is, and where the gap is likely to be.
Pages this one leans on, since a rebuild touches nearly all of them:
- Newport Beach mortgage brokerthe two-unit lot in full — how the other unit's rent counts, and how a two-home property is appraised.
- Orange County jumbo loansthe conforming limits by unit count, and everything that changes once a loan is above them.
- Orange County home equityif the money for the build is coming out of a house you already own, this is how the three ways of reaching it differ.
- Costa Mesa mortgage brokerinland and down the price range — where the question is the conforming line on a single house, not the lot.
Where the guideline and city material came from
The two loan structures and the lesser-of rule are the investor's, read from its guide with the one percentage left there; the fact about the lots is the City's, from the same zoning code the Newport Beach page cites. Nothing here is from a builder or a listing. Check it against the source rather than against me.
- Fannie Mae's Selling Guide describes construction-to-permanent financing as structured with either one closing or two, and on a single-closing purchase measures the loan against the lesser of the purchase price — the sum of the cost of construction and the price of the lot — and the property's appraised value as completed.Read at the source on
- Fannie Mae's Selling Guide describes a renovation mortgage on a purchase as measured against the lesser of the property's as-completed appraised value and the sum of the purchase price and the total renovation costs, and caps the renovation cost at a share of that figure.Read at the source on
- Corona del Mar lies within Newport Beach, whose Zoning Code designates two-unit residential districts meant for no more than two dwellings per legal lot, alongside a single-unit district that excludes condominiums and cooperatives.Read at the source on
Tell me what you'd do with the house, and I'll tell you which loan it is.
Keep it, change it, or replace it — that decision picks the loan, and the loan picks the lenders. Bring the address, your plan for it, and a builder's estimate if you have one, and I will run cost against value before an appraiser does it for you.
- Call or text
- (949) 744-5302
- Office
- 17911 Von Karman Ave, Suite 400
Irvine, CA 92614