
About
Luke McCrea
Orange County native. Chapman graduate. Licensed Realtor and mortgage loan originator, working out of Irvine. Here is the longer version, and the parts of it that matter to your loan.
175+
lenders to shop
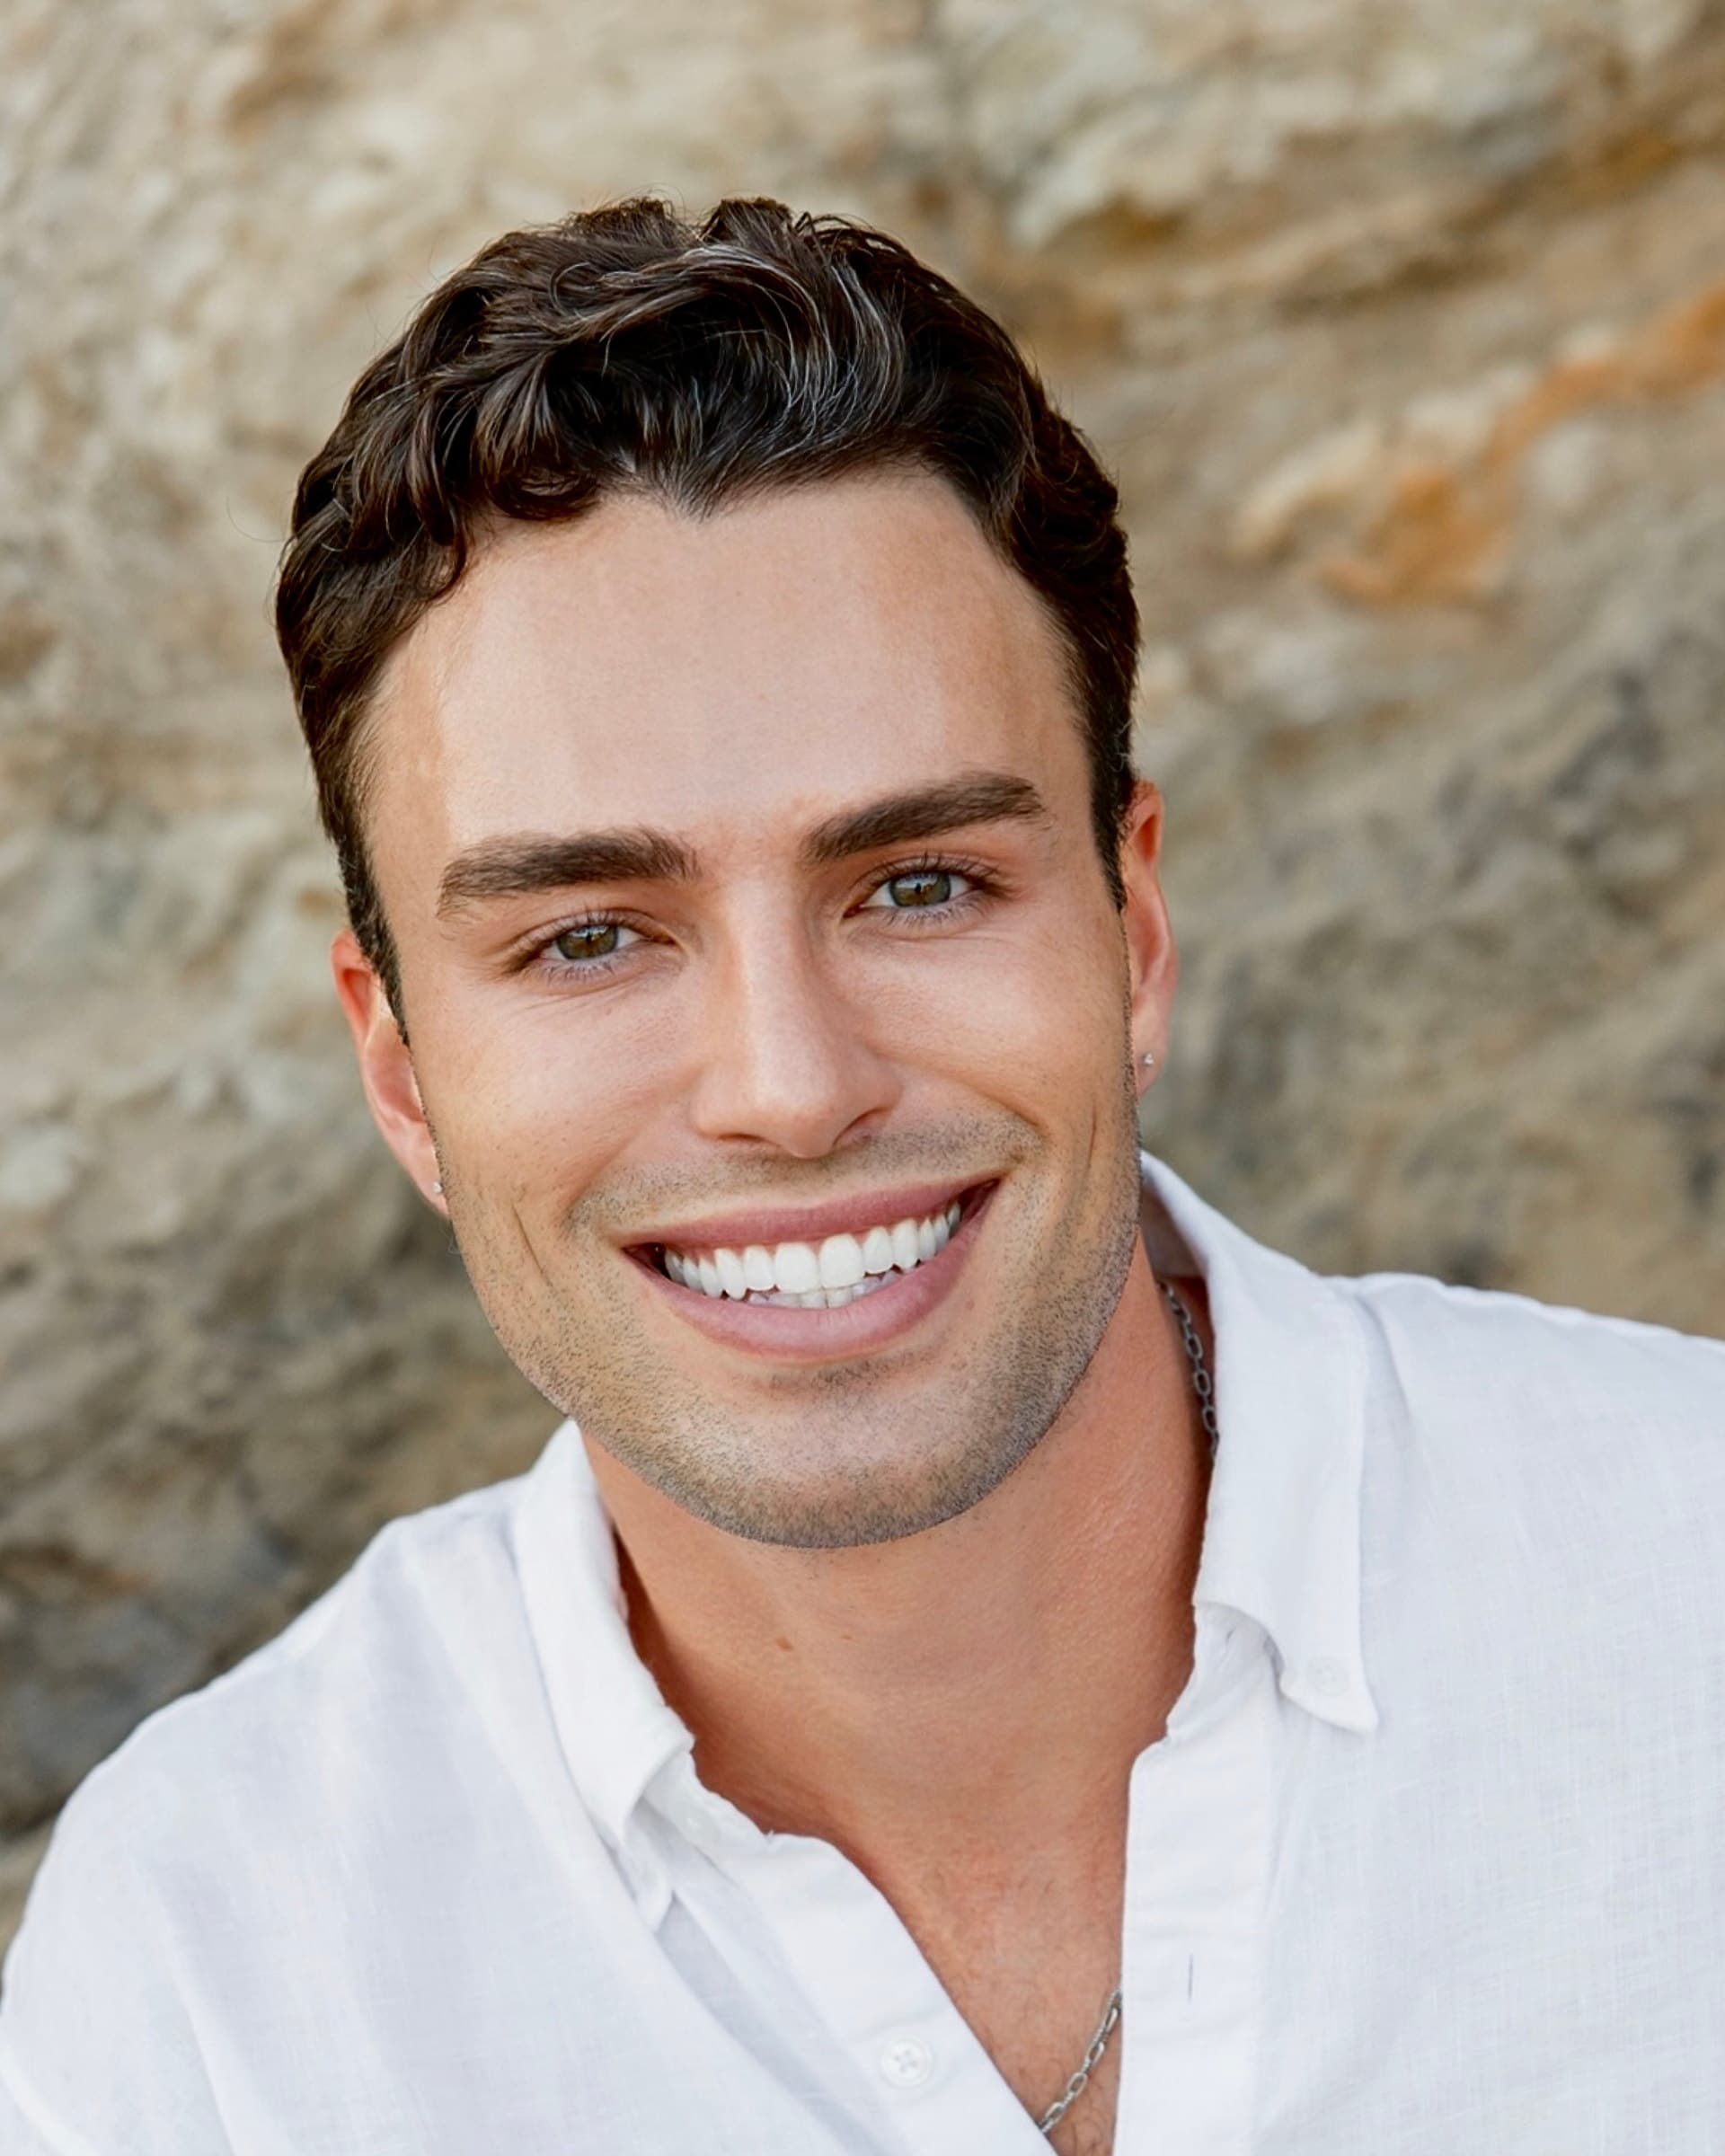
- Name
- Luke McCrea
- Role
- Mortgage Loan Originator
- Education
- Chapman University
- NMLS
- #2588056
- CA DRE
- #02155418
- Brokerage
- West Capital Lending, Inc.
- Office
- 17911 Von Karman Ave, Suite 400, Irvine
- Licensed in
- 28 states
On the record
Where I'm from
I grew up here, and I came back to work here.
Born and raised in Orange County, Chapman University, and now an office in Irvine. When you say you are looking in Costa Mesa but open to Tustin, I know what that trade-off is before you finish the sentence.
Not from a map — from having driven it my whole life. That is worth exactly what it sounds like, and no more. It does not make a loan easier to underwrite.
What it does is make the questions I ask about a property the right ones for this county: whether an addition was permitted, which association answers a lender quickly, what the tax bill on a newer village actually says. And it means I ask them before you write an offer, not after.
The city pages on this site are that knowledge written down — one for Costa Mesa, one for Irvine, one for Newport Beach, each about the one thing that is genuinely different about financing there.
The dinner table
Real estate was the conversation at home.
My father, Phil McCrea, spent more than twenty years in title insurance. I grew up hearing about the deals that closed clean and the deals that fell apart in the last week, and what separated them.
Almost always, it was someone catching a problem early instead of hoping it went away. I learned the business from the paperwork side before I ever wrote a loan, and it is still the side I trust.
It shows up in how I run a file. The document list goes out on day one. The appraisal gets ordered when it should be, not when someone remembers. When something looks like it might become a problem in week three, you hear about it in week one, with what I intend to do about it.
It also shows up in what I will not do, which is tell you a loan is fine before I have read the file. A pre-approval from me means I have looked at the income documents and pulled the credit. It is slower by a day, and worth a great deal more once an offer is on the table.
Both sides of the table
Two licenses, one file.
I hold a California real estate license as well as an originator's license. Most people in this business hold one or the other, and the difference shows up the moment an offer is competitive or an escrow gets complicated.
- The purchase contract and its contingencies
- How your offer looks to the listing agent
- What the seller's counter actually changes
- Where an escrow timeline is likely to slip
- Read the income documents before issuing a letter
- Shop the file across the lenders who want it
- Order the appraisal when it should be ordered
- Call when something moves — and when it doesn't
It means I read the purchase contract, not just the application — how an offer will look to a listing agent, which contingency actually protects you, and how to structure the financing so it survives a competitive bid.
When escrow gets complicated, I am not learning the vocabulary on your time. The figure beside this is the plain version of what each license does on a file; the point is that both halves are read by the same person.
If you are an agent rather than a buyer, the dual license is most of what you would want to know about me. There is a page on this site about how I work a file with you, and what you will hear from me and when.
More options
175+ lenders, and the difference that makes.
I originate through West Capital Lending, which gives me access to more than 175 lenders. A bank has one rate sheet and one set of guidelines, so a file that does not fit gets a no.
I get to take your file to the lender that actually wants it — self-employed income, a jumbo amount, an investment property, credit that needs a little room. Each of those is a file some lenders decline and other lenders are built for.
More options usually means a better fit, and a better fit is where better terms tend to live. Sometimes it just means getting a yes at all, which is the more important half.
Either way the work is the same: know which lenders like which files before your file goes anywhere near them. That is most of what a broker is for, and it is the part you never see.
Where I work
Orange County first. Licensed well beyond it.
Orange County is home and the focus of the practice. I am also licensed in a good many other states, so relocating, buying a second home, or picking up a rental somewhere else is usually still a file I can take.
The full licensed footprint, with the number under each state, is on the licensed-states page.
All six cities beside this are areas I work, and each has a page of its own, because the financing question there is specific enough to deserve one.
If your city is not on that list, ask anyway. It is where the questions come from most, not the edge of where I work.
Out of state, check the licensed-states page before you call — every state, with the license number under it.
How I work
Three things you can hold me to.
Not promises about the loan — a lender decides that, and nobody should tell you otherwise on a website. Promises about me.
Weekdays: same business day.
Call, text or email during the business day and you hear back before it ends. Not a confirmation that I received it — an answer.
Evenings and weekends: within 24 hours.
Offers get written on Saturday nights and countered on Sunday mornings. Outside business hours, a reply inside 24 hours, and usually well inside it.
Always me.
No assistant, no team inbox, no queue. The person who picks up the first call is the person on your file through underwriting and at signing.
These are commitments about how I work. Whether a loan is approved is a lender's decision, and never mine to promise.
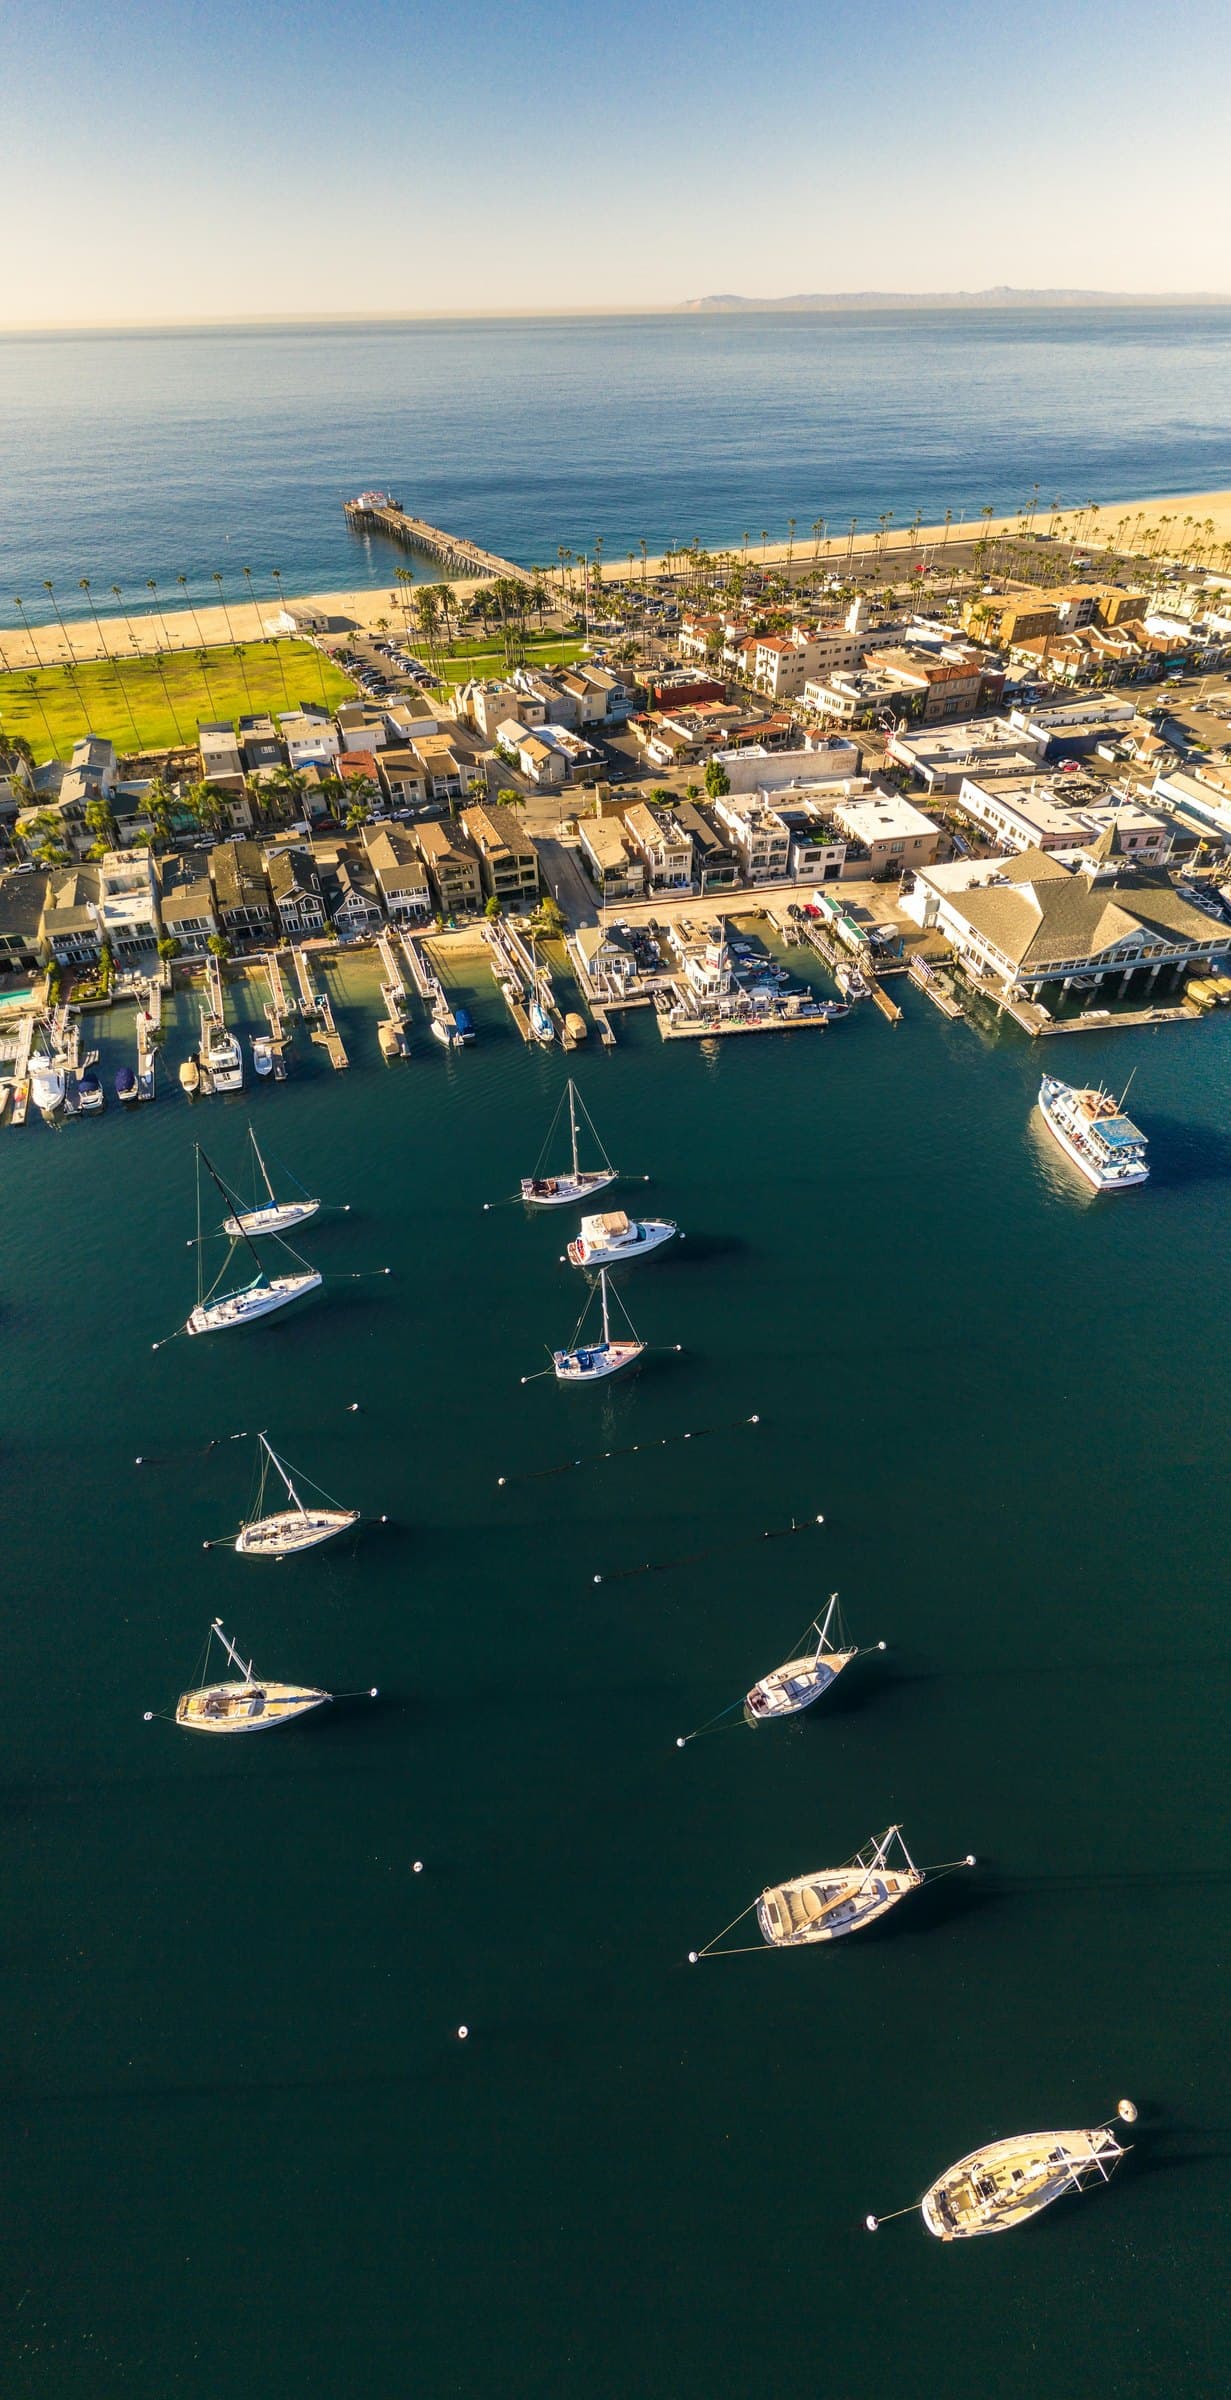
Newport Harbor — the pier and the Peninsula from above.
Let's talk about what you're trying to do.
No pressure and no obligation. I would rather answer your questions early than have you guess.
- Call or text
- (949) 744-5302
- Office
- 17911 Von Karman Ave, Suite 400
Irvine, CA 92614