
Getting a mortgage in Costa Mesa
Most Orange County cities are clearly on one side of the conforming loan limit. Costa Mesa sits on it. Prices here run straight through the band that ceiling falls in, which means the same house can be a conforming loan for one buyer and a jumbo loan for the next, and the number that decides it is not the price. Add the two property questions this city produces more than most — older houses that have been added onto, and accessory dwelling units — and you have most of what makes financing here specific. This is what I'd want you to know before you write an offer.
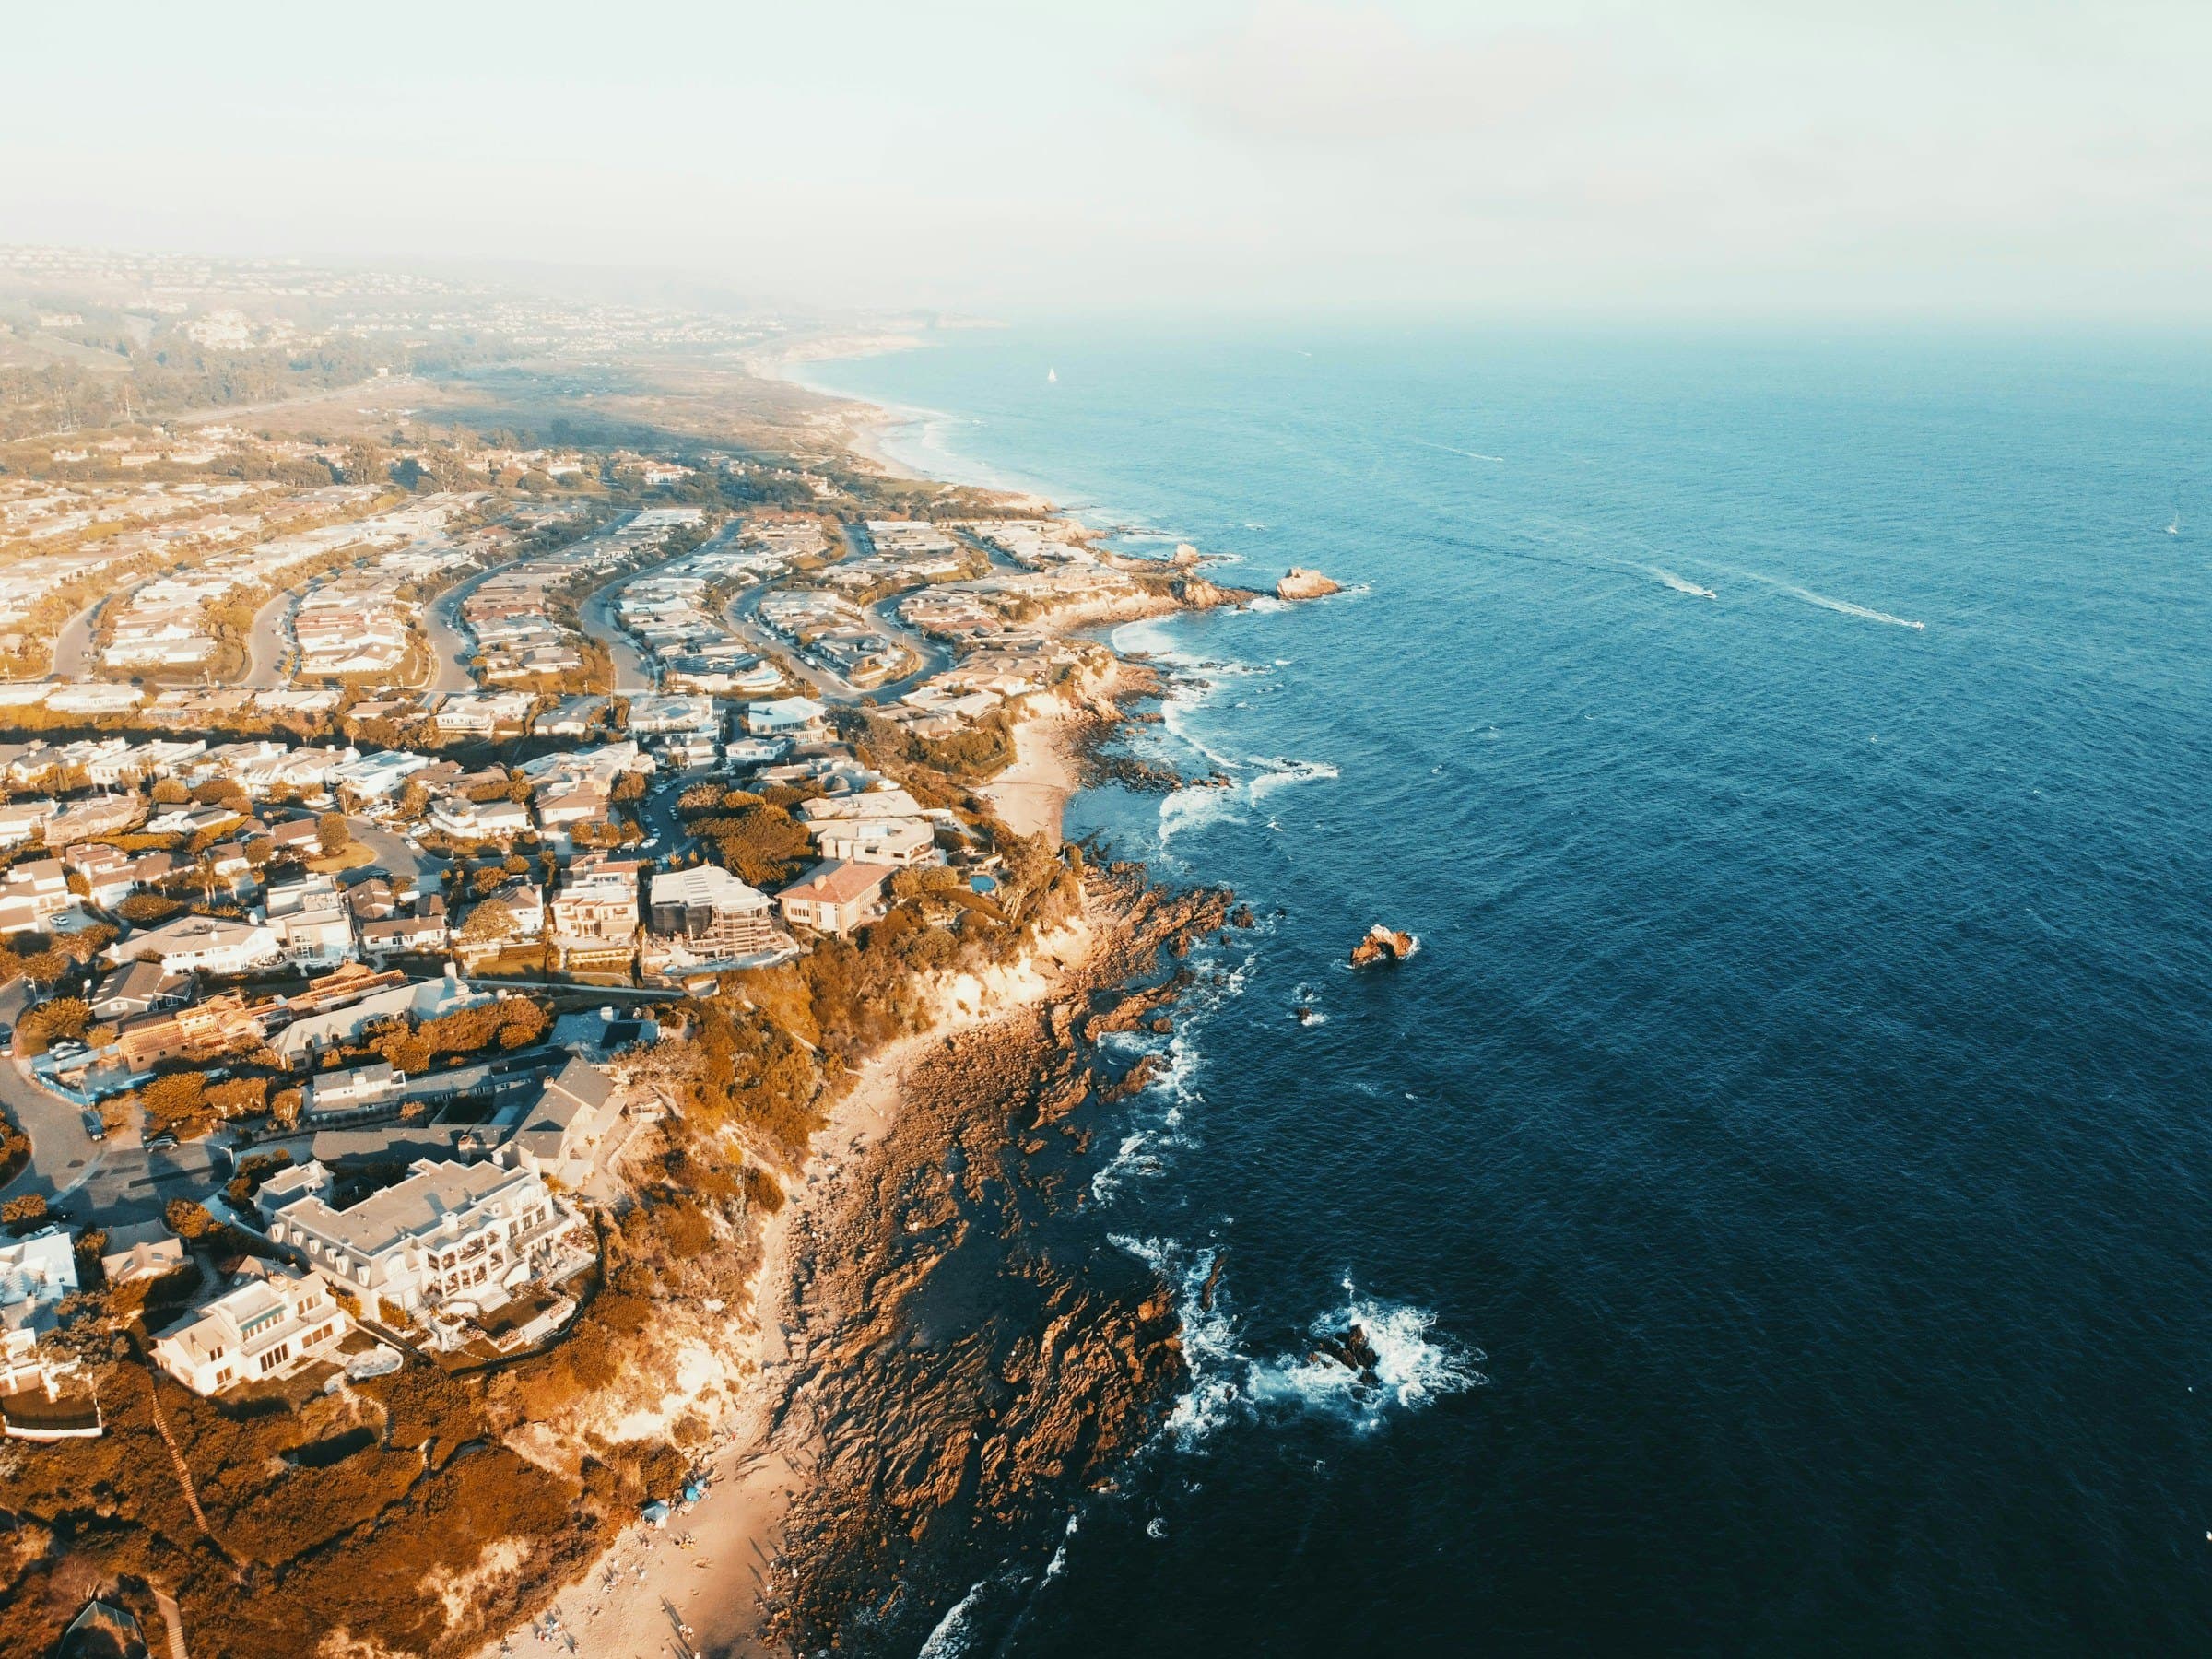
Orange County's coast-adjacent housing from above — the band the conforming limit runs through.
The line
What does a Costa Mesa mortgage actually look like?
Costa Mesa prices run straight through the band the Orange County conforming limit sits in. So the city produces a genuine mix — some files are conforming, some are jumbo, and which one you land in often comes down to what you put down rather than what the house costs.
- Down payment
- Loan amount
- Jumbo
The conforming limit is a county figure, reset for each calendar year, and Orange County's sits at the top of the national range. At or under it, your loan is read against one shared rulebook that every lender in the country is working from. Over it, you are in jumbo, where each lender writes its own rules on reserves, documentation, property type and appetite. The numbers come from the Federal Housing Finance Agency (FHFA) and I keep them on the Orange County jumbo page rather than retyping them here — they move once a year, and a figure copied into six places goes stale in five of them.
Shopping is a different exercise in a city that sits on the line. Well above the ceiling, you know on the first showing that you are a jumbo borrower, and you can go find the lenders who like that kind of file. Well below it, the question never comes up. Costa Mesa gives you neither. Two houses on the same block can put you under two different sets of underwriting rules, and so can one house bought by two different people.
The practical version: settle the structure before you write an offer, not after. A pre-approval built on one rulebook and then used to buy under the other is not a small correction. It is a different document list, a different underwriting read, and sometimes a different lender entirely.
Who is buying
Who is actually buying in Costa Mesa?
In this market it is mostly first-time buyers on the Eastside, renters who have decided to stop renting, and people who wanted Newport and did the math. That mix matters for financing, because it means down payment assistance and conforming programs do more work here than they do closer to the water.
Assistance is the first thing people ask about, and the honest answer has two halves. The programs are real, and I will run them for anyone they fit. But nearly all of them cap the purchase price, and those caps were not drawn with this part of the county in mind — a good share of what sells in Costa Mesa is above them. Where they do reach is the lower end of the inventory: condominiums, townhomes, the smaller houses. The Orange County first-time buyer page carries each program, what it caps, and the date I last read it off the administering agency's own site.
For a renter buying a first house, the file itself is usually less dramatic than expected. Two years of income in a form a lender can read, a paper trail showing where the down payment came from and how long it has been yours, and credit that has not been reshuffled in the last few months. Gift money is ordinary and has its own paperwork. What tends to catch people is not the loan, it is the estimate: lenders build the property tax line off what you are paying for the house, not off what the seller pays today, and on a Costa Mesa house that has not changed hands in decades those two numbers are nowhere near each other.
The Newport half of the mix is worth saying plainly, because a lot of people arrive here from that search. Moving inland does not simply make the loan easier as the price comes down — it changes the loan's shape. A file that was heading for jumbo can land conforming, which brings a different set of rules and, on some files, mortgage insurance into the monthly payment. That is not a downgrade. It is a different conversation, and it is better had before the offer than during escrow.
Older houses
How does Costa Mesa's older housing stock affect an appraisal?
A lot of this city was built decades ago and has been added onto since. Appraisers care whether that added square footage was permitted, because unpermitted space generally cannot be counted toward value. Pulling the permit history before you are in escrow is cheaper than discovering the gap after the appraisal comes back.
- Cash you bring to closing
- A price you renegotiate
- A purchase that ends
An appraiser is answering a narrower question than most buyers expect: what have comparable properties nearby actually sold for, and how does this one measure against them. Square footage sits at the centre of that comparison, and not all square footage counts. Space added without permits is generally excluded from the living area an appraiser reports, however finished it looks and however long it has been there. It may pick up some value as an amenity. It does not get counted as house.
Here that comes up constantly, because the additions are constantly there. Converted garages. Enclosed patios. A bedroom off the back that appeared sometime in the eighties. Two houses can be advertised at the same size when only one of them is that size on the record, and a listing is not where that gets settled.
So pull the permit history while you are still shopping. Ask the listing agent for it, and ask what the record shows rather than what the seller remembers. It is a cheap errand at that stage and an expensive one halfway through a contingency period.
What is at stake is the gap. A lender lends against the appraised value or the purchase price, whichever is lower, so an appraisal that lands short does not make the difference disappear — it turns into cash you bring, a price you renegotiate, or a purchase that ends. All three are survivable. None of them is something you want to meet in the last week.
Accessory units
I have an ADU, or I want one. What does that do to the loan?
It changes two things at once: what the property is worth and what income can be used to qualify. A permitted unit can be counted on both. An unpermitted one usually counts for neither. Costa Mesa runs a program for legalizing units built before 2020, and it is worth knowing about before you apply.
| The unit | Counted toward value? | Rent counted as income? |
|---|---|---|
| Permitted | Generally yes — it is part of the property. | Sometimes, depending on the lender and how the rent is documented. |
| Unpermitted | Generally no. The money that built it is not money the appraisal gives back. | Generally not at all. |
Take the two directions separately, because they fail separately. On value: a permitted unit is part of the property and an appraiser can treat it that way. An unpermitted one generally cannot be counted toward the value of the house, which means the money that went into building it is not money the appraisal gives back. On income: rent from a legal, permitted unit can sometimes count as qualifying income, depending on the lender and on how the rent is documented. Rent from an unpermitted unit generally cannot be counted at all.
The city runs a route for owners in the second position. Its Safe ADU Legalization Program is offered for accessory dwelling units and junior units built without permits before 2020. An owner can ask the city to inspect the unit before applying rather than after — and where that inspection turns up health and safety items, the city says it will not penalize the owner for having had the unpermitted unit, provided the permits needed to correct them get pulled. That order is the useful part: the look comes first. The city's own page is linked in the sources at the end, with the date I read it.
The financing consequence is the part that belongs to me, and it runs in an order people do not expect. Legalizing a unit costs money — permits, corrections, sometimes real construction — and the rent it will eventually produce cannot pay for the work, because that income only becomes usable once the unit is legal. The money is needed first. For an owner who has been in the house a long time, that gap usually gets bridged with equity, which is a decision with its own page here and its own reasons to say no.
One more, because it decides who is worth approaching: lenders differ, and differ widely, on what they will do with a property that has an unpermitted unit on it. Some will not lend on it. Some will lend and instruct the appraiser to value the house as though the unit were not there. Mention it on the first call rather than in underwriting. It changes the shortlist, and a shortlist is far easier to change than an escrow.
The decision
How does the same Costa Mesa house end up conforming for one buyer and jumbo for another?
Because the limit applies to the loan, not the house. Two buyers can agree the same price and land on opposite sides of the conforming ceiling depending on what they bring to closing. It is the one number that quietly decides which set of underwriting rules your file is read under, and almost nobody asks about it first.
The mechanics deserve to be spelled out, because the decision lives inside them. The ceiling is tested against the loan amount. The loan amount is the price less what you put down. So the variable that decides which rulebook reads your file is the one you control — and it is the one nobody has settled yet when they start walking through houses on a Sunday.
Which does not mean ducking under the ceiling is automatically right. Sometimes it is. Conforming underwriting is more predictable and the same file gets read much the same way anywhere, and that is worth something on a competitive offer. Sometimes it is not. Cash pushed into the down payment to cross the line is cash that has left your reserves, and on a house of this age the reserves are what pay for the roof in the first year. And occasionally the jumbo option prices and structures better than the conforming one and the whole exercise was unnecessary.
So it is a both-ways calculation, and running it takes one conversation rather than a spreadsheet. What I want to keep you out of is the version where the choice gets made by accident — where a buyer picks a down payment because it is a round number and finds out in underwriting which rulebook that put them under. Bring it up before you settle on the number, not after.
If a friend were buying in Costa Mesa, I'd tell them to really pay attention to the neighborhood, because Costa Mesa can feel completely different from one pocket to the next. I grew up here, so I've seen firsthand how much the city has changed and how desirable certain areas have become. Eastside, Mesa Verde, and the neighborhoods around the Back Bay all offer something different. Don't just look at the house — make sure you love the specific part of Costa Mesa you're buying into.
Costa Mesa questions I get asked
- Do I need a jumbo loan to buy in Costa Mesa?
- Not necessarily, and the asking price on its own will not tell you. The conforming ceiling is tested against the loan amount rather than the purchase price, so two buyers agreeing the same number can end up on opposite sides of it. Work out the loan amount first and the rest follows from there.
- Can rent from an ADU be used as income on my loan?
- Sometimes, if the unit is permitted and the rent is documented the way the lender wants it. Guidelines differ on how much of it counts and what proof they ask for. Rent from an unpermitted unit generally cannot be used at all, which is usually the more important half of the answer.
- The listing says the house is bigger than the public record. What is going on?
- Usually an addition, and the question is whether it was permitted. An appraiser generally reports only permitted space as living area, so that difference can move the value a lender is willing to lend against. Ask for the permit history while you are still shopping rather than once you are in escrow.
- I have an unpermitted converted garage. Is that a dealbreaker?
- It is a lender-selection question more than a yes or a no. Some lenders will not take a property with unpermitted space on it; others will, and will simply value the house without counting it. Tell me early and I can point the file at lenders who will consider it at all.
- Are there down payment assistance programs that work in Costa Mesa?
- Some, at the lower end of the price range. Nearly every assistance program caps the purchase price, and a good share of what sells here is above those caps. The Orange County first-time buyer page lists each one with its ceiling and the date I last checked it against the agency's own site.
- Do you actually work in Costa Mesa?
- Yes — Costa Mesa is one of the areas I work, and I grew up in Orange County. What that is worth on a file here is knowing which questions to ask about a specific property: how an addition is likely to be treated, what the permit record needs to show, and what a listing agent wants to see in a pre-approval letter.
Pages this one leans on, if you want the longer version of any of it:
- Orange County jumbo loansthe conforming limit itself — where the figures come from, what they are by unit count, how the county compares with the ones next door, and when they were last checked.
- Orange County first-time buyersdown payment assistance program by program, what each one caps, and an honest read on which ones reach prices in this part of the county.
- Orange County home equityif the money for a remodel, an addition, or legalizing a unit is going to come out of the house, this is how the three ways of reaching it differ — and when the answer should be no.
- Irvine mortgage brokernext door, and an almost opposite question. There the property questions are about the association rather than the house — a condo loan is underwritten on the building as well as on you.
Where the city material came from
Programs change and pages move. Here is what was read, where it was read, and when — go and check it against the city rather than against me.
Let's work out which loan this house actually is.
Bring the address, the price you are thinking about, and roughly what you plan to put down. That is enough to tell you which side of the limit you land on and what this city's property questions are likely to do to the file. If there is an addition or a unit out back, lead with that.
- Call or text
- (949) 744-5302
- Office
- 17911 Von Karman Ave, Suite 400
Irvine, CA 92614